Dalio argues that the United States is entering a vicious cycle in which debt expansion and shrinking demand reinforce each other: rising interest rates drive up borrowing costs, further expanding the debt pile; as overseas demand shifts, both China and Japan—two major creditors—have incentives to reduce their holdings. Considering the combined outlook for new bond supply and changing demand, shorting U.S. Treasuries has become easier than going long. Meanwhile, corporate bonds and the AI‑driven financing boom are intensifying competition for capital, leaving the corporate credit market akin to a "canary in a coal mine." Debt‑service costs are eroding fiscal space, while global debt‑related competition is mounting, making it difficult for equity markets to remain insulated. Overall, the supply of financial assets—spanning both debt and equity—appears far outstripping what demand can absorb.
Ray Dalio, co-founder of hedge fund giant Bridgewater Associates, has once again sounded the alarm on U.S. Treasury bonds: the sell-off in Treasuries is far from bottoming out, and a structural supply‑demand imbalance is pushing U.S. debt into a crisis of historic proportions.
On Tuesday, the 13th, Eastern Time, Ray Dalio posted on LinkedIn that the United States is entering a vicious cycle in which debt expansion and shrinking demand reinforce each other: rising interest rates drive up borrowing costs, which in turn expand the debt burden. This spiral will persist until "the economy and financial markets are sufficiently strained and supply and demand return to equilibrium," he wrote. "The U.S. bond bear market may still have a long way to go."
 Dalio's remarks stand in stark contrast to the positions of institutions such as Blackrock and Morgan Stanley Investment Management. The latter have turned bullish after the 10-year U.S. Treasury yield surged earlier this month to a 2002 high, approaching 5.4%. According to reports, the Bloomberg index tracking U.S. Treasuries has fallen by about 2.4% year-to-date, with U.S. Treasury prices on track for their first annual decline since 2022.
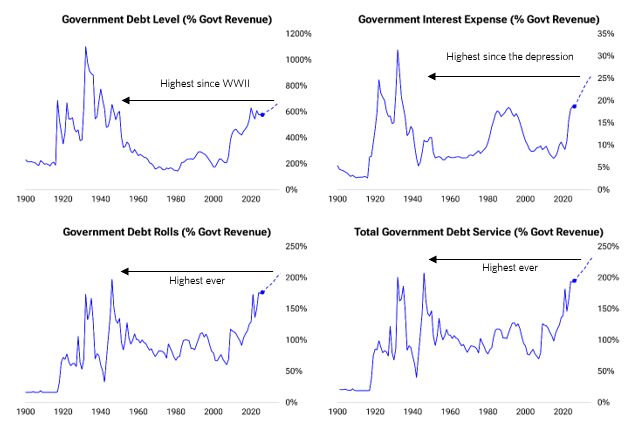
U.S. government debt has risen to its highest level since World War II.
In his article, Dalio backs his assessment with extensive data. He estimates that, measured by the total size of outstanding debt and the ratio of debt-servicing costs to government revenue, U.S. government debt has now reached its highest level since World War II and is expected to continue deteriorating over the next few years.
As of the end of September 2026, the outstanding marketable U.S. Treasury debt stood at approximately $32 trillion, up 8% from a year earlier. To date this year, the U.S. Treasury has net‑issued about $1.5 trillion in new debt, with full-year net issuance expected to reach $2.1 trillion. At the same time, the Treasury must also roll over roughly $10 trillion in maturing debt.
Dalio warns that even a modest decline in investors' willingness to reinvest could create a substantial funding gap.
In terms of its debt structure, the U.S. Treasury is increasingly turning to short-term securities issuance to ease the pressure from supply-demand imbalances in the long-end bond market. Currently, short-term notes account for roughly 50% of total issuance, well above the historical norm of around 20%—a share typically seen only during economic recessions.
Dalio pointed out that while short-term issuance helps temporarily reduce interest expenses, it also significantly increases the risk of debt rollover and drives up debt-servicing costs during periods of rising interest rates.
Overseas demand for U.S. Treasuries is shifting, with China and Japan playing a particularly crucial role.
Dalio views the contraction in external demand as one of the key factors weighing on the U.S. bond market. He notes that overseas investors currently hold roughly $9.3 trillion in U.S. Treasuries, making them the largest single group of holders—accounting for about 32% of outstanding debt—but their pace of purchases is slowing even as supply continues to rise.
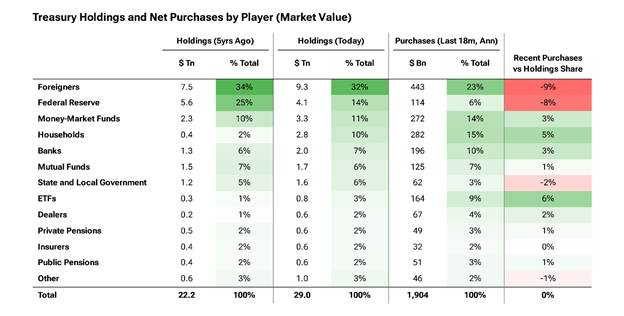
Among the major foreign holders of U.S. Treasury securities, Japan and China deserve the closest attention. According to Ray Dalio, Japan holds roughly $1.1 trillion in U.S. Treasuries, with about $600 billion held as official reserves and approximately $230 billion managed by Japan's Government Pension Investment Fund (GPIF).
He believes that Japanese policymakers have a strong incentive to encourage domestic institutions to reduce their holdings of U.S. Treasuries and repatriate capital, thereby supporting the yen and stabilizing the Japanese government bond market. Rising yields on Japanese government bonds would further reinforce this trend, while the unwinding of related yen‑carry‑trade positions could also deliver a sharp shock to the market.
On the Chinese side, Dalio stated that official U.S. statistics significantly understate the true size of China's holdings. He roughly estimates that Chinese corporations and individuals hold about $1 trillion in U.S. Treasury securities, while China's foreign-exchange reserves hold an additional roughly $2 trillion, bringing the total value of China's financial assets in the United States to as much as $4 trillion. As the renminbi appreciates, China's dollar‑denominated assets face exchange‑rate losses, further increasing its incentive to reduce its holdings.
He warned that if only 10% of private U.S. dollar holdings were hedged or converted, it could trigger roughly $400 billion in dollar sell-offs—enough to have a significant impact on both the exchange rate and credit markets.
Dalio wrote: "Taken together, the anticipated shifts in new bond supply and demand have long—indeed, continue to—made shorting U.S. Treasuries easier than going long."
Corporate bonds and the AI‑driven financing boom are intensifying competition for capital.
Dalio pointed out that the Treasury does not raise funds in isolation; rather, it competes on equal footing with all other borrowers and asset issuers. In addition to roughly $2.1 trillion in net new federal borrowing, corporate debt is expected to increase by about $1.4 trillion. When combined with household and local‑government borrowing, the total net fixed‑income financing needs for 2027 will approach $4.4 trillion—excluding maturing debt that must be rolled over.
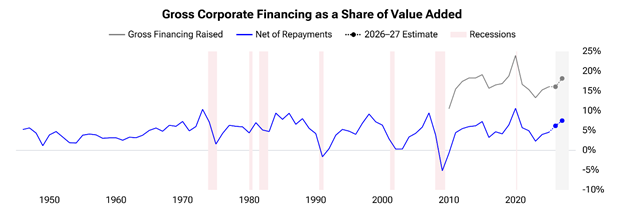
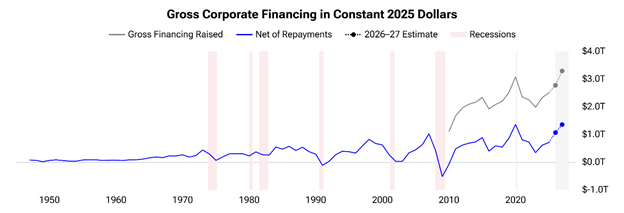
The structural shifts in the corporate bond market deserve particular attention. According to Ray Dalio, the total size of U.S. corporate bonds stands at roughly $15.7 trillion, and driven by a surge in capital spending on artificial intelligence (AI), overall corporate bond issuance has risen nearly 30% year over year this year. Notably, bond issuance by AI hyperscale computing firms reached approximately $220 billion in the first half of 2026, compared with just about $108 billion for the entire year of 2025.
Even more concerning is that high capital expenditures are squeezing corporate free cash flow, credit spreads have begun to widen, and investors are demanding greater "concessions" before they will absorb new supply.
Dalio likened the corporate credit market to "the canary in the coal mine," arguing that it serves as an early indicator of mounting stress across the broader financial markets.
Debt-servicing costs are eroding fiscal space.
In addition to supply-demand imbalances, Dalio also emphasized the constraining effect of debt-servicing costs on fiscal space.
He pointed out that, with the outstanding marketable Treasury debt standing at roughly $32 trillion, a one-percentage-point increase in overall interest rates would add approximately $310 billion annually to interest payments alone, and over a decade would boost the government's debt by about $3 trillion.
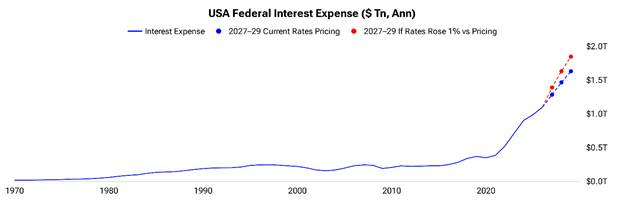
Currently, the average interest rate on U.S. outstanding debt stands at around 3.5%, while market rates are already in the 4% to 5.5% range.
Dalio pointed out that even if interest rates stop rising, interest expenses will continue to climb as maturing debt is refinanced at higher rates. According to Treasury data, net interest payments for the first three quarters of fiscal year 2026 increased by $78 billion year over year, a rise of 10%.
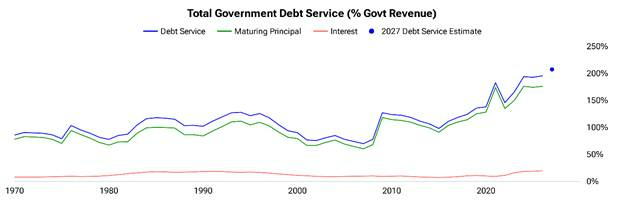
He further noted that the scale of principal‑rollover debt has risen to roughly 185% of federal tax revenues, while total debt‑service costs now account for about 200% of government tax receipts—and are still climbing—making the risk of a "death spiral" increasingly difficult to ignore.
Global debt competition is intensifying, leaving stock markets unable to remain unaffected.
Dalio extends his analytical perspective to a global scale.
He cited data indicating that, in 2025, the total borrowing by governments of OECD member countries reached a record $17 trillion, and is projected to rise further to approximately $18 trillion in 2026—up 17% from 2024 and roughly double the level of a decade earlier. European nations are ramping up sovereign bond issuance to finance defense and infrastructure, with Germany expected to issue bonds totaling around €576 billion in 2027, even as the European Central Bank, during the same period, is reducing rather than expanding its holdings of government bonds.
Regarding the stock market, Ray Dalio has also sounded a warning. He notes that over the past year, corporations have shifted from net buyers to net sellers—i.e., financiers—in the equity market, with the annualized value of equity issuance in the first half of 2026 already reaching $1.8 trillion, largely driven by the AI‑related investment boom. He expects that pressure on equity financing through IPOs, secondary offerings, and private placements will persist going forward.
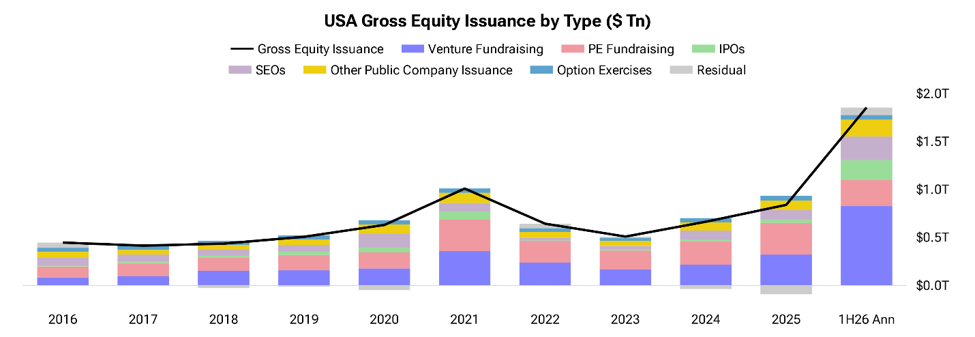
Dalio concludes that "the supply of financial assets—including both debt and equity—appears to far exceed the level that demand can absorb."
He noted that the market is currently in the mid‑cycle phase—following a sharp rise in interest rates but before it has yet triggered a significant decline in equity markets and risk assets. Interest rates are expected to remain on an upward trajectory until supply‑demand imbalances begin to ease, at which point rate‑sensitive markets and economic sectors will come under pressure first.
Editor/stephen