Market Snapshot
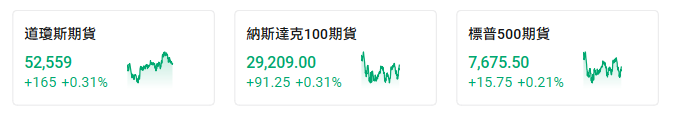
Ahead of Monday's open, futures for all three major indices rose. Last week, the market focused on AI debt issues, with Dow Jones Industrial Average futures up 0.31%, Nasdaq Composite futures up 0.31%, and S&P 500 futures up 0.21%.
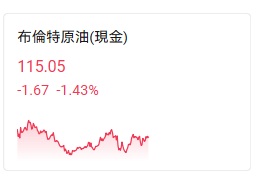
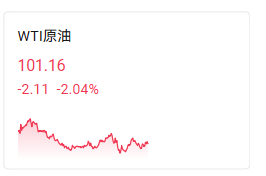
Trump said on Sunday that he would not launch strikes that day, and summarized his options as either reaching an agreement with Iran or "dealing with them once and for all." International oil prices fell,$WTI Crude Oil Futures Main Contract (2611)(CLmain.US)$Down 2%,$Brent Crude Oil (Cash) Futures Main Contract (2612)(BZmain.US)$Down 1.43%.
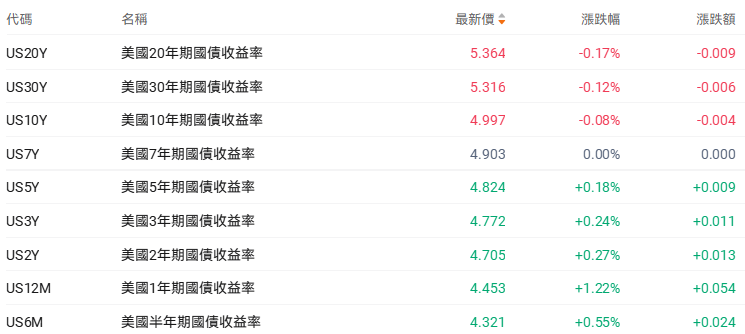
Most U.S. Treasury bonds rose,$U.S. 10-Year Treasury Yield (US10Y.BD)$Maintain at a high level.
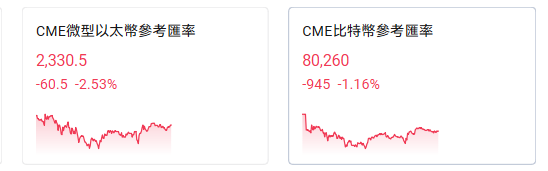
 Cryptocurrencies are down.
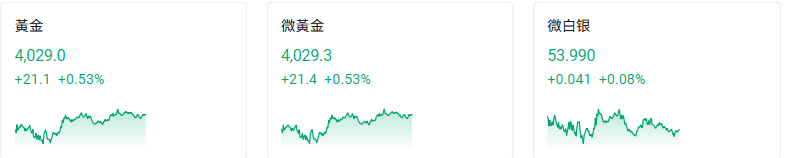
Precious metals edged higher.
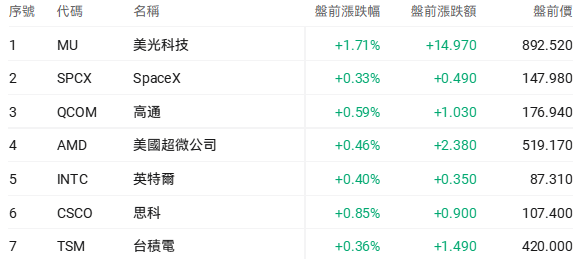
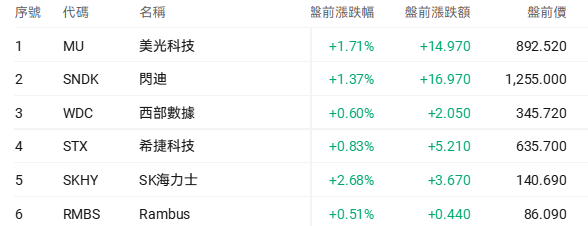
$Star Technology Stocks (LIST2518.US)$Pre-market, most stocks rose, with Micron Technology up 1.71% and Cisco up nearly 1%.
$Storage Concept (LIST23925.US)$Stocks rose in pre-market trading, with SK Hynix up more than 2% and SanDisk gaining over 1%.
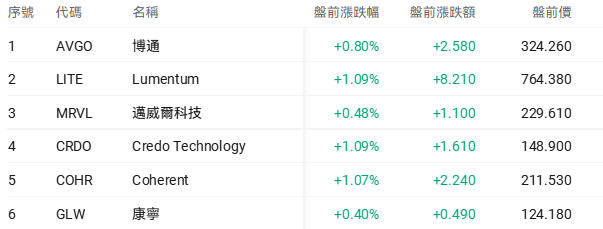
$Optical Communications (LIST23979.US)$Concept stocks rose collectively in pre-market trading, with Lumentum, Coherent, and Credo Technology all gaining more than 1%.
Individual Stock News
Meta launches an equity financing round of approximately $35 billion, with NVIDIA, AMD, and Broadcom planning to subscribe.
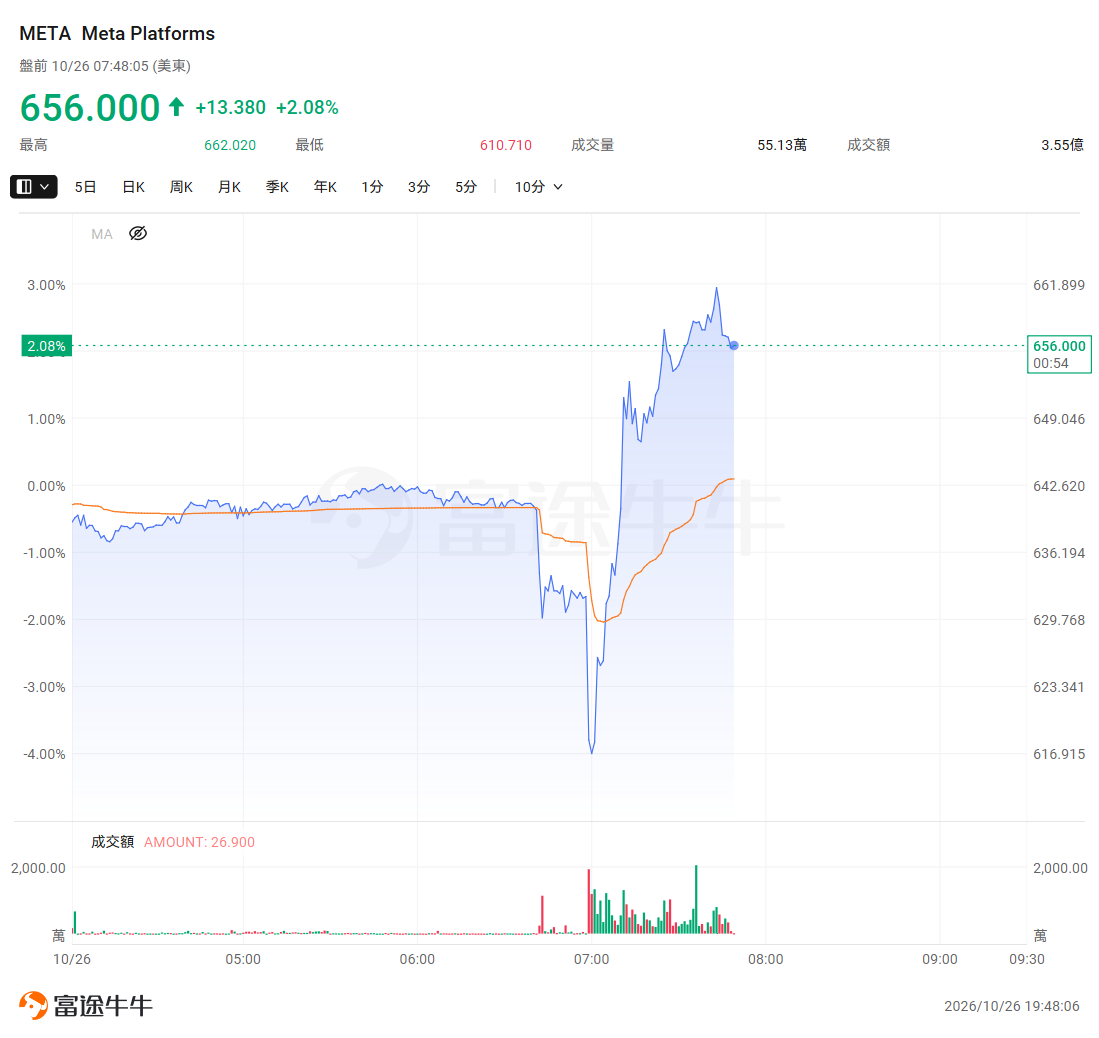
$Meta Platforms(META.US)$Announced the simultaneous launch of two public offerings totaling approximately $35 billion: first, the issuance of $22.5 billion in Class A common stock through forward sale agreements; second, the issuance of depositary shares representing roughly $12.5 billion in mandatory convertible preferred stock. The company expects to grant underwriters a 30-day overallotment option to purchase up to an additional 37.5 million depositary shares and up to $3.375 billion in Class A common stock, with Morgan Stanley and Goldman Sachs serving as joint lead bookrunners. NVIDIA, AMD, and Broadcom have all indicated non-binding intentions to collectively subscribe for up to $5 billion in Class A common stock at the same price and terms. Meta stated that the proceeds will be used for general corporate purposes, including investments in AI infrastructure, and forecasts capital expenditures of $135–$145 billion by 2026. In addition, Meta plans to launch a market‑based offering of approximately $60 billion in Class C common stock starting in the first quarter of 2027. Meta's pre-market shares rose more than 2%.
Lula's unexpected re-election has sent Brazilian assets in the U.S. tumbling across the board.
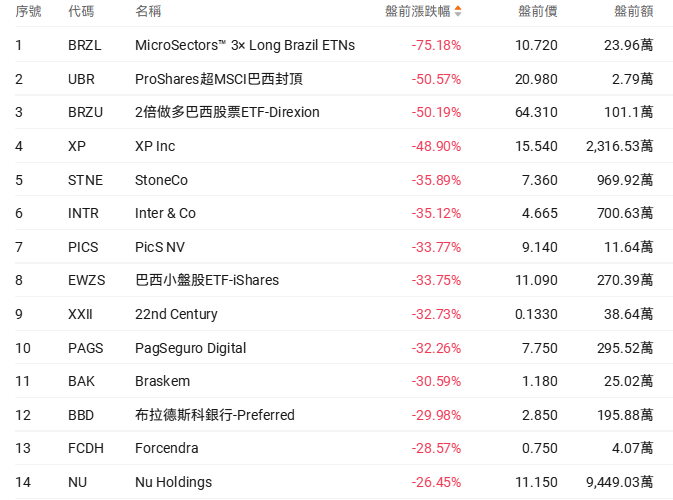
As of press time,$MSCI Brazil Index ETF - iShares (EWZ.US)$Down more than 33% in pre-market trading,$Petroleo Brasileiro SA Petrobras (PBR.US)$Down 20%,$Itau Unibanco (ITUB.US)$Down more than 26%,$Bradesco Bank-Preferred (BBD.US)$Down more than 30%,$Nu Holdings(NU.US)$Down nearly 26%,$XP Inc(XP.US)$Down nearly 48%,$MercadoLibre(MELI.US)$It fell by more than 14%. According to data from Brazil's Superior Electoral Court, left-wing incumbent President Lula defeated Senator Flávio Bolsonaro in Sunday's presidential runoff, winning an unprecedented fourth term with 51.8% of the vote to 48.2%. Reuters reported that Bolsonaro refused to concede, saying he would seek to have the results annulled. Earlier, markets had widely bet on a victory for the more market‑friendly Bolsonaro, which had fueled expectations of economic reforms; since the first round, Brazil's stock market has surged nearly 7%, and the real has appreciated by almost 5%.
Musk said that more than 200 new cloud providers will "die in droves," putting renewed pressure on CoreWeave and others.
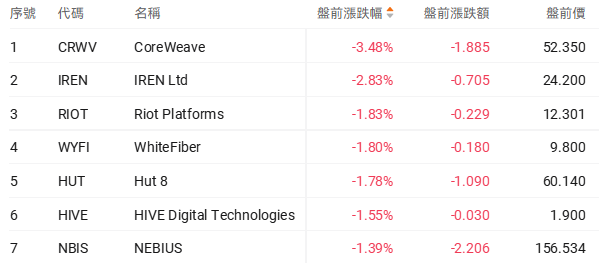
On Sunday, Musk posted on X that over the past few weeks, the debt markets have virtually cut off financing to companies that lack substantial revenue streams independent of AI data centers. "This means that more than 200 new‑generation cloud providers are headed for a 'guppy‑style' wave of mass failures and consolidation—some will survive, but not many," he wrote. Musk also stated that…$SpaceX(SPCX.US)$It will not acquire any new cloud service providers.$NEBIUS(NBIS.US)$CEO Volozh previously acknowledged that some funding sources have temporarily dried up, but the company has sufficient funds to complete its 1-gigawatt expansion plan; Nebius announced last Thursday that it had secured $3.5 billion in debt financing from Citi. According to CNBC, over the past month, both CoreWeave and Nebius shares have fallen by more than 30%, while Iren has dropped by approximately 40%. As of press time,$CoreWeave(CRWV.US)$It fell nearly 4% in pre-market trading,$NEBIUS(NBIS.US)$Down more than 1%,$IREN Ltd(IREN.US)$Down nearly 3%.
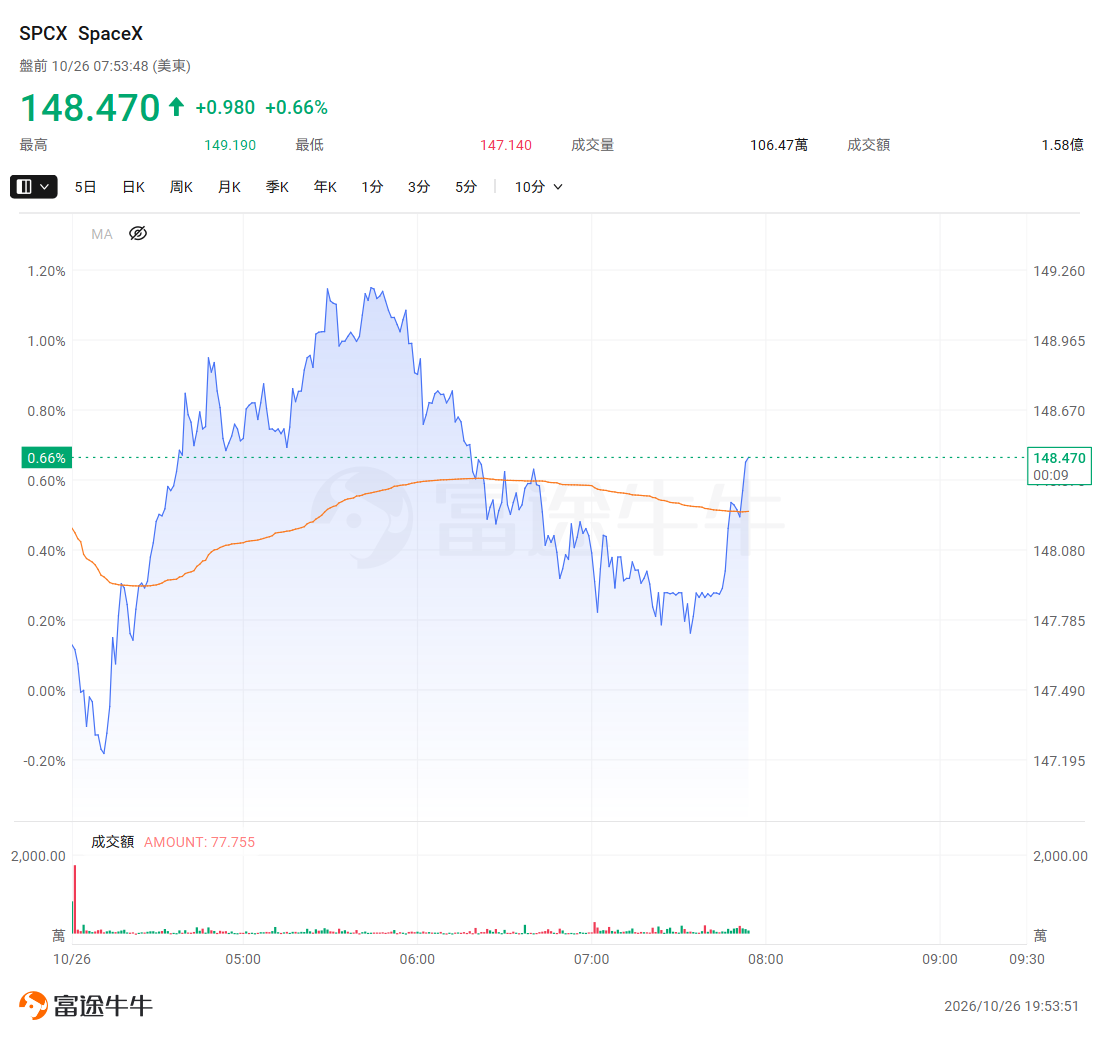
SpaceX has completed $40 billion in debt financing to procure GPUs.
On Sunday, Musk stated on X that,$SpaceX(SPCX.US)$It has secured $40 billion in debt financing to purchase GPUs that power artificial intelligence systems. He stated that SpaceX holds an investment-grade credit rating and generates revenue from its Starlink satellite internet and rocket launch businesses. In a subsequent post, Musk added that this financing is primarily in the form of redeemable debt, with funds expected to be available in the first and second quarters of 2027. Earlier, Bloomberg, citing sources familiar with the matter, reported that SpaceX is in talks with banks and investors to raise $40 billion to buy NVIDIA chips, planning to structure the financing through special-purpose entities so that the debt would not appear on SpaceX's balance sheet, thereby preserving its investment-grade credit rating. According to CNBC, SpaceX operates its own data centers and sells computing power, making it a direct competitor to emerging cloud service providers.
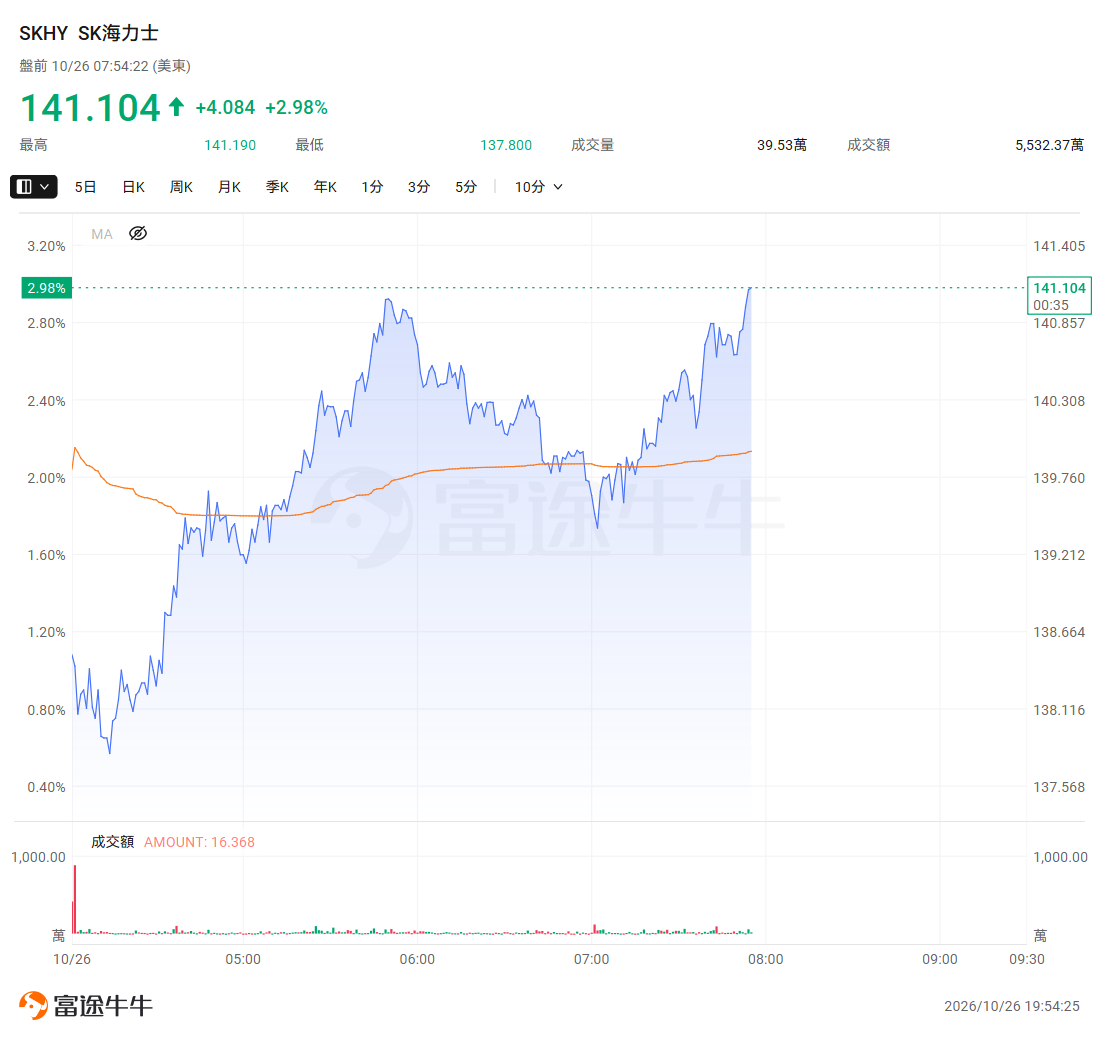
SK Hynix announced on Wednesday a shareholder return plan, which may include a special dividend of approximately US$12 billion.
Previously, there were reports that,$SK Hynix (SKHY.US)$It is considering distributing a special dividend of approximately 16 trillion won (about US$12 billion), primarily derived from the roughly 20 trillion won in gains recorded in the first half of this year from its stake in Kioxia. SK Hynix responded that the company is evaluating various shareholder return options, and no decision has been made yet on a special dividend; relevant measures will be announced alongside its third-quarter results following a board resolution on October 28. The company has also halted its assessment of Solidigm's U.S. IPO. As of press time, SK Hynix was up nearly 3% in pre-market trading.
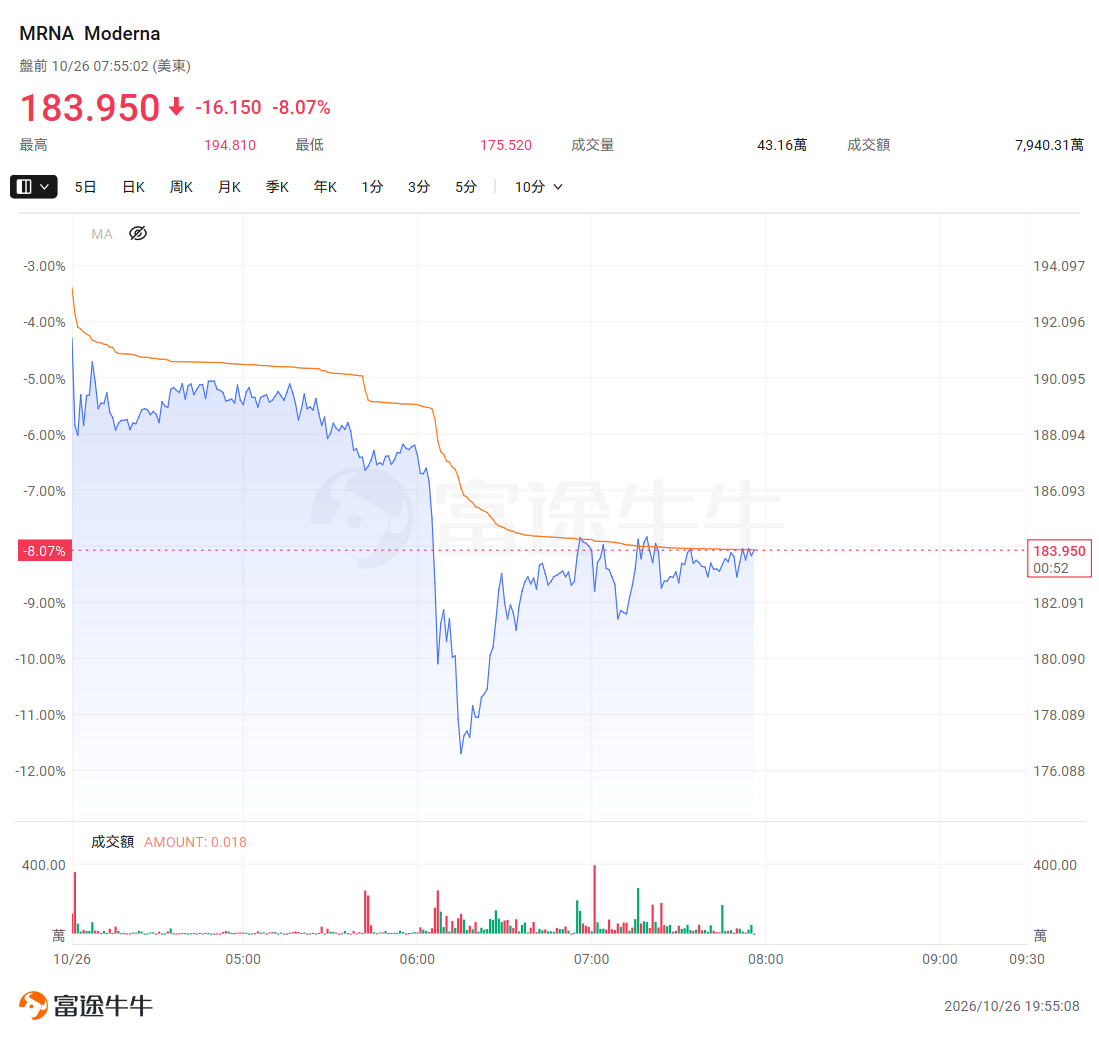
Moderna releases full cancer vaccine data, shares fall further in pre-market trading.
$Moderna(MRNA.US)$and$Merck & Co. (MRK.US)$On Saturday, at the ESMO Congress' presidential symposium, the full Phase III INTerpath-001 data were unveiled for the personalized mRNA cancer vaccine intismeran in combination with Keytruda as adjuvant therapy following surgery for melanoma. With a median follow-up of 24.6 months, the combination regimen reduced the risk of recurrence or death by 42% compared with Keytruda alone, and lowered the risk of distant metastasis or death by 38%. The 2-year relapse-free survival rate was 82.2% versus 70.0%. However, overall survival data remain immature and have not yet reached the pre-specified significance threshold (HR 0.77); confidence intervals for some smaller subgroups span 1, including the U.S. subgroup's distant metastasis outcomes based on just 10 events. Following an earlier leak of partial data on October 22, Moderna's stock plunged as much as 26% that day, closing down 17.57%. As of press time, Moderna was trading more than 8% lower in pre-market trading.
Apple's first foldable-screen iPhone Duo sold out immediately upon release, with **** media reporting that Apple has asked suppliers to increase orders by 30%.
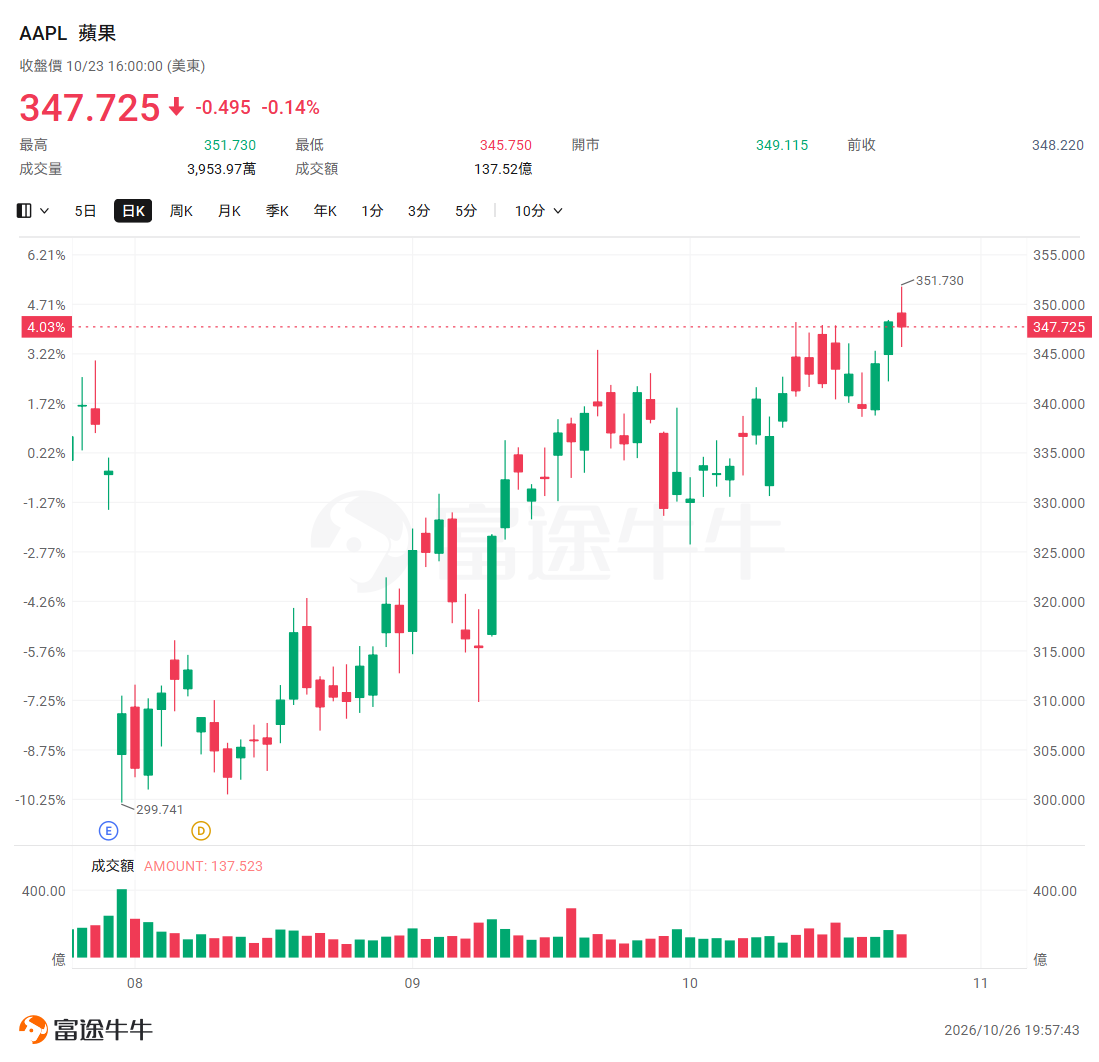
$Apple(AAPL.US)$The first foldable-screen phone, the iPhone Duo, launched globally on October 23, with a starting price of $1,999 and high-storage versions exceeding $3,000; it sold out almost immediately after release. On Monday, Taiwan's Economic Daily, citing industry insiders, reported that Apple has asked its supply chain to ramp up production and increase orders by 30%. The iPhone Duo's annual shipments are now projected to rise from roughly 6 million units to between 8 million and 10 million this year, with potential to reach 33 million units by 2027. The second wave of shipments is expected to begin on January 22; Apple has yet to comment. It's worth noting that reports of a 30% order increase had already surfaced in mid-month, and this latest report further revises the shipment forecast. The iPhone Duo is assembled by Foxconn, while its core processor is manufactured by Taiwan Semiconductor. Meanwhile, users in multiple regions have reported screen cracks on some iPhone Duos, though Apple has not yet responded. In terms of stock performance, Apple's market capitalization briefly surpassed NVIDIA's during Friday's trading session, but it closed slightly below NVIDIA's.
Amazon CEO: AWS's capacity for 2027 is virtually sold out, and most of 2028 has already been booked.
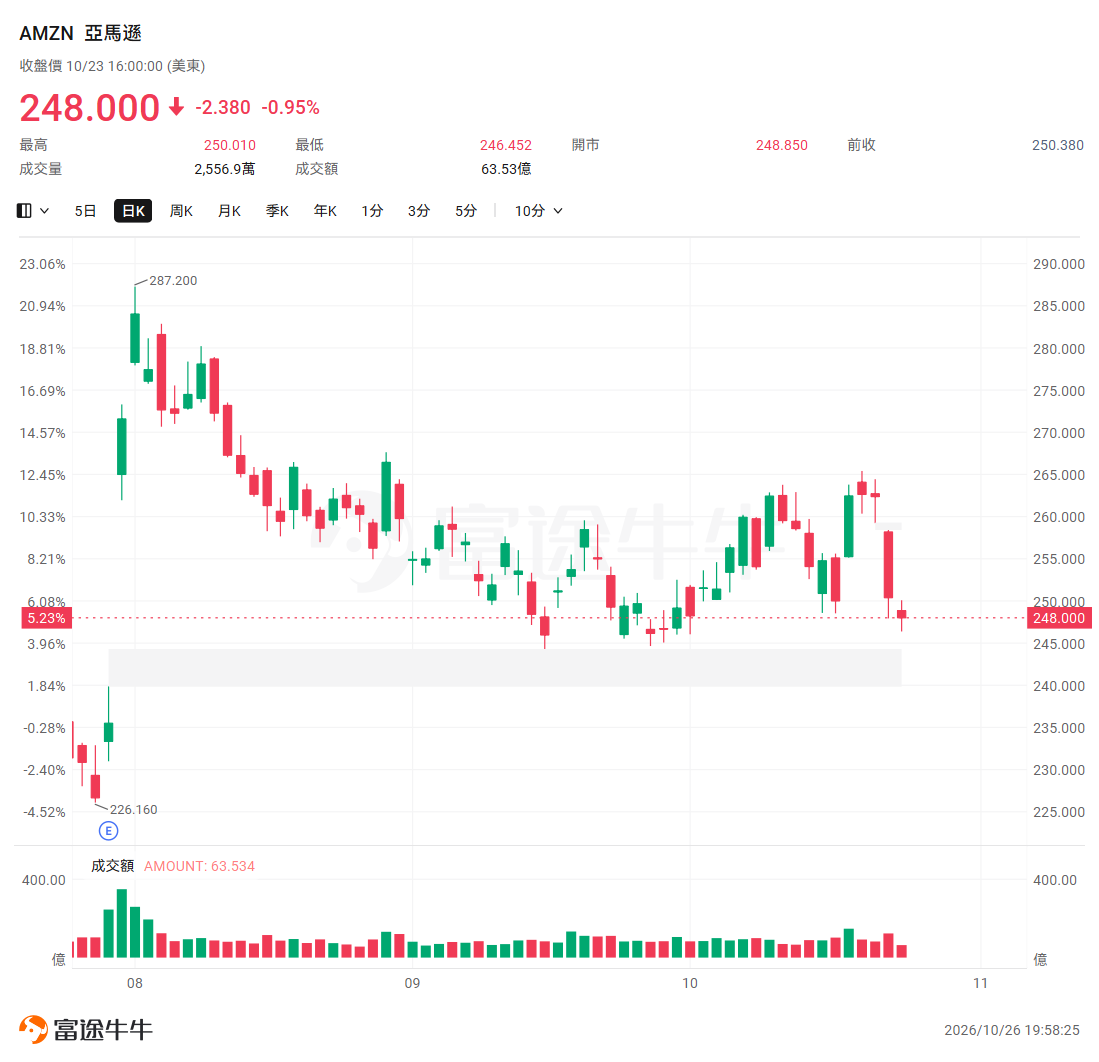
$Amazon (AMZN.US)$CEO Andy Jassy said last Friday on a16z's video podcast that AWS's cloud-computing capacity is fully booked through 2026, largely booked through 2027, and a significant portion of its capacity for 2028 has also been reserved. He noted that the company will always reserve some capacity for on-demand services and inference services like Bedrock and EC2, but "virtually all of the large blocks of capacity have been sold out." Jassy added that Amazon is struggling to keep up with the robust demand from its AI labs and enterprise customers, and given that capacity is already fully booked, the company "can invest more capital without it being a poor use of capital." Earlier this year, Amazon projected capital expenditures of approximately $220 billion for 2026. The podcast was hosted by a16z co-founder Ben Horowitz and partner Erik Torenberg. According to Reuters, Amazon is scheduled to release its third-quarter earnings on October 29 (Thursday, Eastern Time).
Bon Secours is in talks to acquire a majority stake in Surgery Partners, at an estimated valuation of approximately $6 billion.
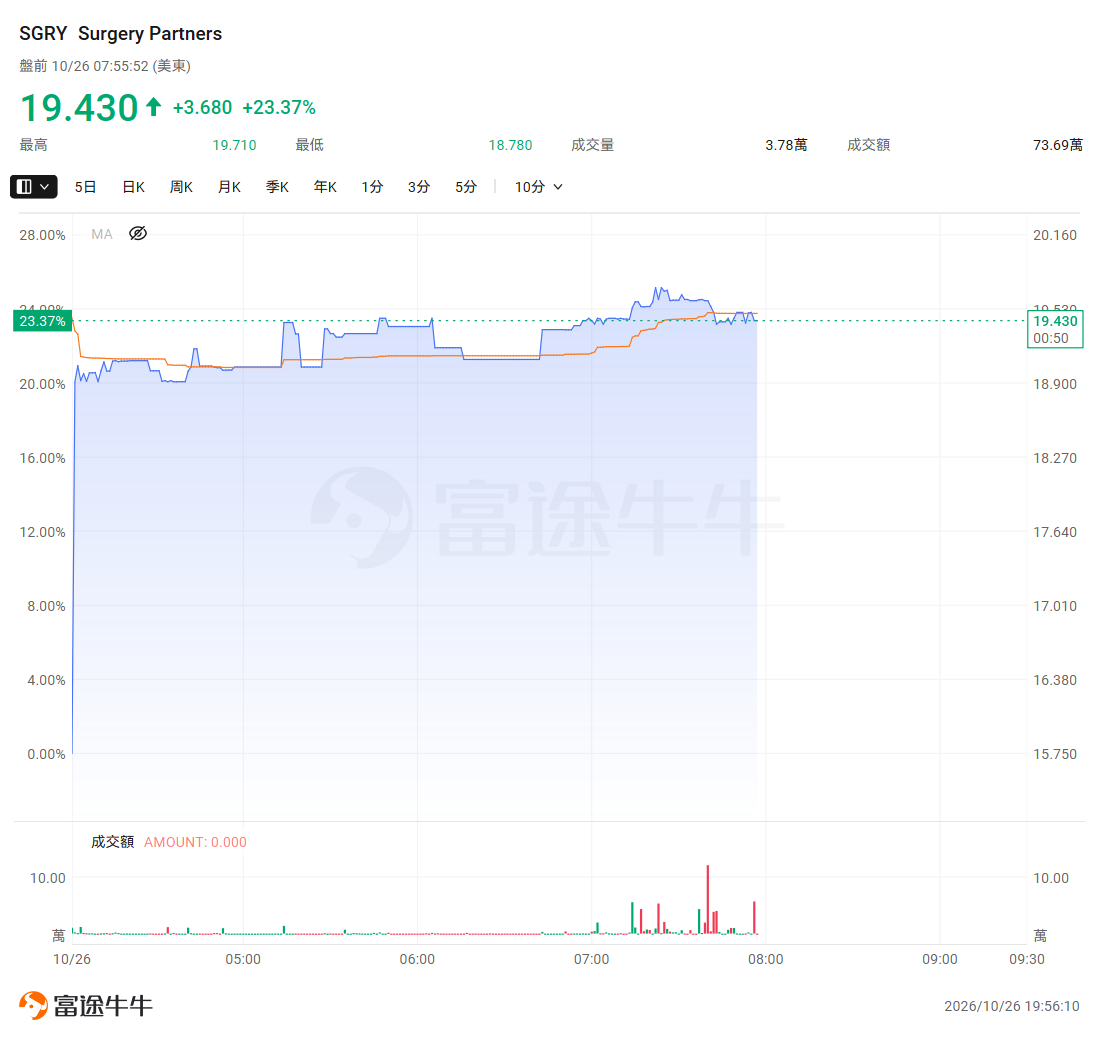
According to the UK's Financial Times, the nonprofit healthcare group Bon Secours Mercy Health is in talks to acquire an operator of outpatient surgical centers.$Surgery Partners(SGRY.US)$Late-stage negotiations are underway for a majority stake, valuing the privatization deal at approximately $6 billion, including debt—equivalent to about $20 per share, roughly 27% above its Friday closing price of $15.75. According to reports, Bain Capital, the private equity firm that currently holds nearly 40% of Surgery Partners, will retain its stake, and the deal could be announced as early as Monday. No official confirmation has yet been issued by the parties involved. As of press time, Surgery Partners was up nearly 24% in pre-market trading.
Global Macro
The Federal Reserve held its benchmark interest rate steady at its Wednesday policy meeting, with markets betting on no change and a rate hike in December.
The Federal Reserve will announce its interest-rate decision on Wednesday, October 28, Eastern Time. According to CNBC, federal funds futures indicate that the market assigns roughly a 90% probability to the Fed keeping the benchmark rate in the 3.75%–4% range. Meanwhile, CME FedWatch shows traders pricing in about a 75% chance of a December rate hike. Disagreements among institutions persist: Bank of America economist Claudio Irigoyen expects the Fed to raise rates by 25 basis points this week, noting that the October meeting will test Chair Jerome Powell's resolve to alter his forward guidance strategy. If the Fed hikes, investors may worry about overtightening; if it holds steady, the market could question the Fed's credibility in combating inflation. Goldman Sachs, in a report, forecasts that the Fed will skip a rate hike in October but may deliver a second increase in December, with the primary risk being oil prices rising above its projections—largely reflecting market concerns over a potential resurgence of U.S.–Iran tensions.
Super Central Bank Week, coupled with GDP and PCE data, makes for a packed U.S. economic calendar.
In addition to the Federal Reserve, the European Central Bank and the Bank of Japan are set to announce their interest-rate decisions on Thursday and Friday, respectively, with markets expecting both to hold rates steady. According to Reuters, investors are also betting on rate hikes this week from the Bank of Canada and the Reserve Bank of New Zealand, with the latter widely expected to raise rates on Wednesday. On the U.S. data front, Tuesday will see the release of September ADP employment change, September durable-goods orders, and the October consumer-confidence index; Thursday will bring third-quarter GDP, the September PCE price index, and the weekly initial jobless claims. Reuters reports that markets anticipate the core PCE year-on-year rate remaining at a high of 3.1% in September, while third-quarter GDP is forecast to post an annualized growth rate of 3.2%, partly supported by robust spending on data centers. Chris Weston, Head of Research at Pepperstone, noted that forward guidance may prove more important than the rate decision itself, with the key lying in how policymakers shape market expectations for upcoming meetings.
Trump said the U.S.-Russia-Ukraine trilateral talks would be held "very soon," while the Kremlin stated that negotiations could resume after November 4.
On October 25, local time, U.S. President Trump stated that trilateral talks among the United States, Ukraine, and Russia on the Ukraine issue would take place "very soon," though he did not specify a concrete date. He added that both Ukraine and Russia are eager to reach an agreement. Ukrainian President Volodymyr Zelenskyy confirmed that the three parties plan to hold technical-level working talks in November, with the venue still under negotiation; Abu Dhabi and other locations are being considered. Initial discussions are expected to focus on ceasefires related to energy infrastructure and the Black Sea region. Russian Presidential Aide Yuri Ushakov said Moscow is prepared to resume trilateral negotiations after November 4, but cautioned that the first round of contacts is merely a "trial run" and that overly high expectations should be avoided. Earlier, the White House announced that, with U.S. mediation, Ukraine and Russia have agreed to a partial humanitarian ceasefire in Oleshky, set to begin on October 29. On Monday, the Kremlin indicated that this ceasefire could set a precedent for similar arrangements in other regions. In addition, Trump described the oil deal reached with Russia as "a very good thing."
Trump says he may use force against Iran again, while Qatari mediators head to Tehran.
The U.S.-Iran situation remains the focal point of the energy market. According to Reuters, U.S. President Trump said last Friday that the United States might once again take military action against Iran, while Iran has threatened retaliation, including attacks on undersea cables. Al Jazeera, citing reports, stated that U.S. Central Command has prepared plans to strike Iran, with potential targets including energy facilities, infrastructure, and nuclear sites, though no order has yet been issued. On Sunday, Trump said he would not launch an attack that day, adding that his options boil down to either reaching an agreement with Iran or "completely dealing with them." Earlier reports had suggested that the United States and Israel might plan to strike Iran after the U.S. midterm elections on November 3. Meanwhile, a knowledgeable official told Reuters that Qatari mediators were in Tehran on Sunday, coordinating with the United States to help de-escalate regional tensions. Reuters noted that Monday's pullback in oil prices from their recent highs may be partly related to this development.
S&P: Rising Local Opposition in the U.S. Is Increasing Credit Risks for Data Centers
S&P Global Ratings released a report last Friday stating that opposition from local communities to data centers is becoming a significant factor affecting project creditworthiness. The report found that 146 data center projects in the United States have been delayed or canceled, with roughly three-quarters linked to local resistance. The report focuses on moratoriums in states such as New York, Texas, Pennsylvania, Illinois, and Arizona. S&P analysts, including Chris Mooney, noted that delays caused by grid capacity constraints, environmental sustainability concerns, and zoning adjustments "could increase downward pressure on the credit profiles of data center projects." If moratoriums, slower approval processes, or policy reversals lead to substantial project delays, developers may face rent abatements or even the risk of tenants terminating their leases. S&P stated that, for now, the impact on ratings remains limited. On the same day, S&P disclosed that it has rated 32 digital infrastructure transactions in North America, with total debt issuance amounting to $105.3 billion.
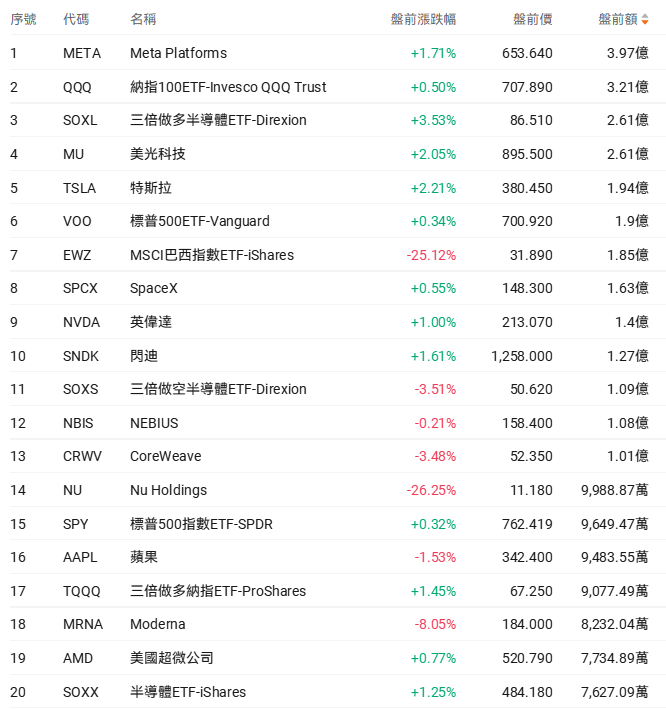
Top 20 Stocks by Pre-Market Trading Volume in the U.S. Market
U.S. Stock Market Macro Calendar Reminder
(The following is in Beijing Time)
22:30 U.S. October Dallas Fed Business Activity Index
After-hours earnings
$Cadence Design Systems (CDNS.US)$ 、 $Celestica (CLS.US)$ 、 $Rambus(RMBS.US)$ 、 $Aimark Technology (AMKR.US)$
 Want to pick stocks or analyze them? Curious about your portfolio's opportunities and risks? For all your investment questions,Just ask Futubull AI!
Editor/rocky