Market Snapshot
Ahead of Thursday's market open, the U.S. core PCE price index for September posted a year-on-year rate of 3.1%, slightly up from last month's 3.0% and in line with market expectations. Following the earnings report, Google's sharp decline weighed on tech stocks, while Amazon, Intel, and SanDisk released their financial results after hours tonight.
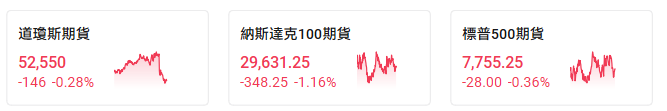
U.S. stock index futures pared their losses slightly after the release of economic data. As of press time, all three major index futures were lower: Nasdaq futures were down more than 1%, Dow Jones futures fell 0.28%, and S&P 500 futures dropped 0.36%.
The following are the market conditions prior to the PCE release.
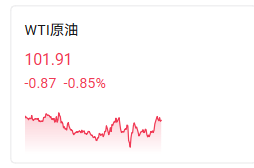
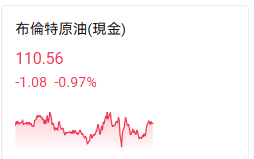
 International oil prices edged lower, with WTI crude trading around $102 per barrel and Brent crude near $110 per barrel. U.S. Vice President Harris sent a letter to Iran seeking to restart peace talks, easing supply concerns.
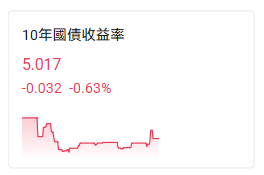
$U.S. 10-Year Treasury Yield (US10Y.BD)$It is quoted near 5.01%, remaining above 5%.
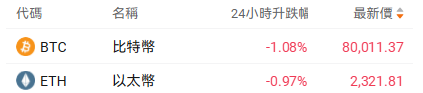
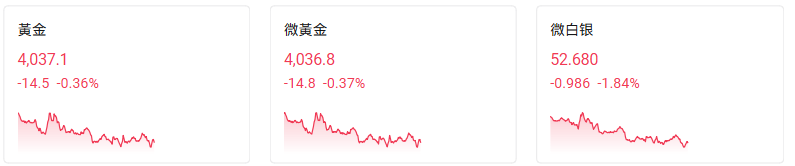
Bitcoin fell more than 1%, trading near $80,000. Precious metals declined, with COMEX gold futures edging lower to around $4,037 per ounce, while silver futures dropped more than 2% to $52.68 per ounce.
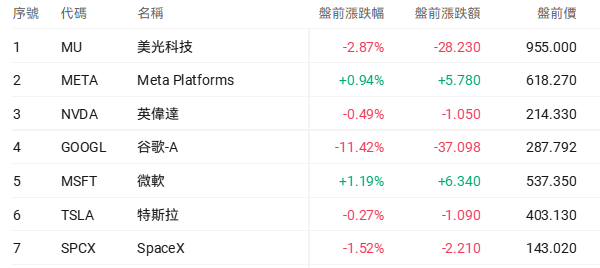
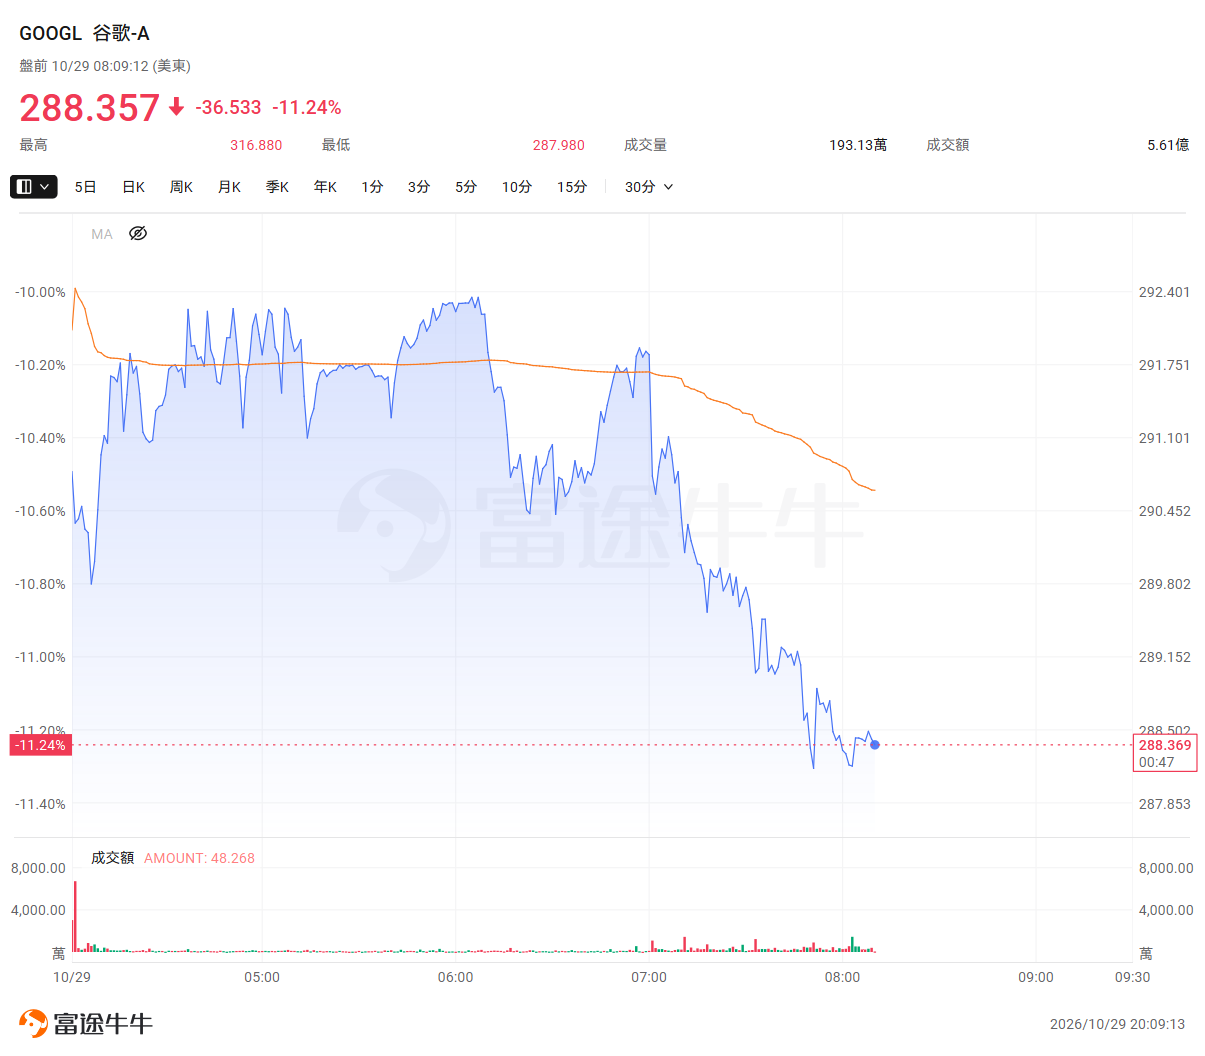
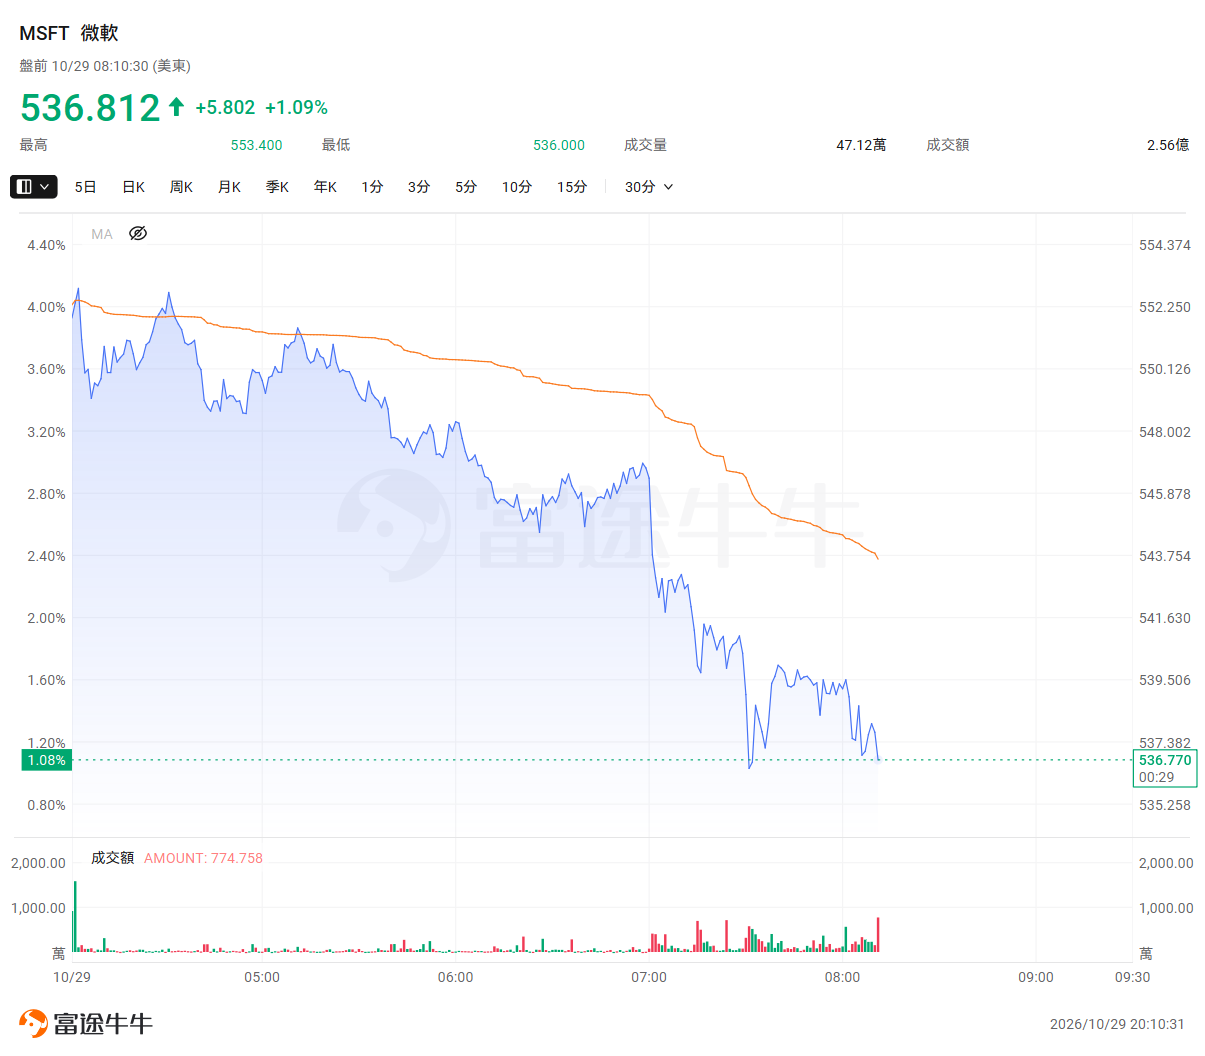
$Star Technology Stocks (LIST2518.US)$Post-earnings divergence: Google-A fell more than 11%, while Microsoft edged up.
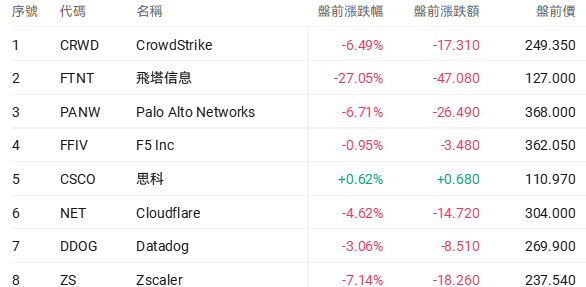
$Cybersecurity Concepts (LIST2570.US)$, software stocks plunged, with Fortinet down nearly 27%, ServiceNow down nearly 19%, Palo Alto Networks down nearly 7%, CrowdStrike down over 6%, and Salesforce down nearly 6%.
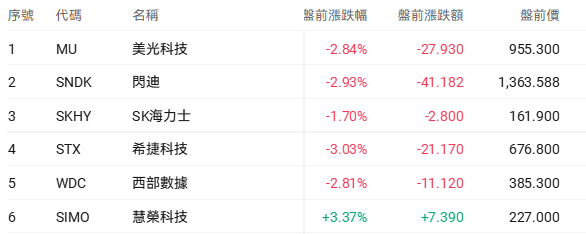
$Storage Concept (LIST23925.US)$Downward trend: SanDisk and Seagate Technology fell nearly 3%, while SK Hynix dropped nearly 2%.
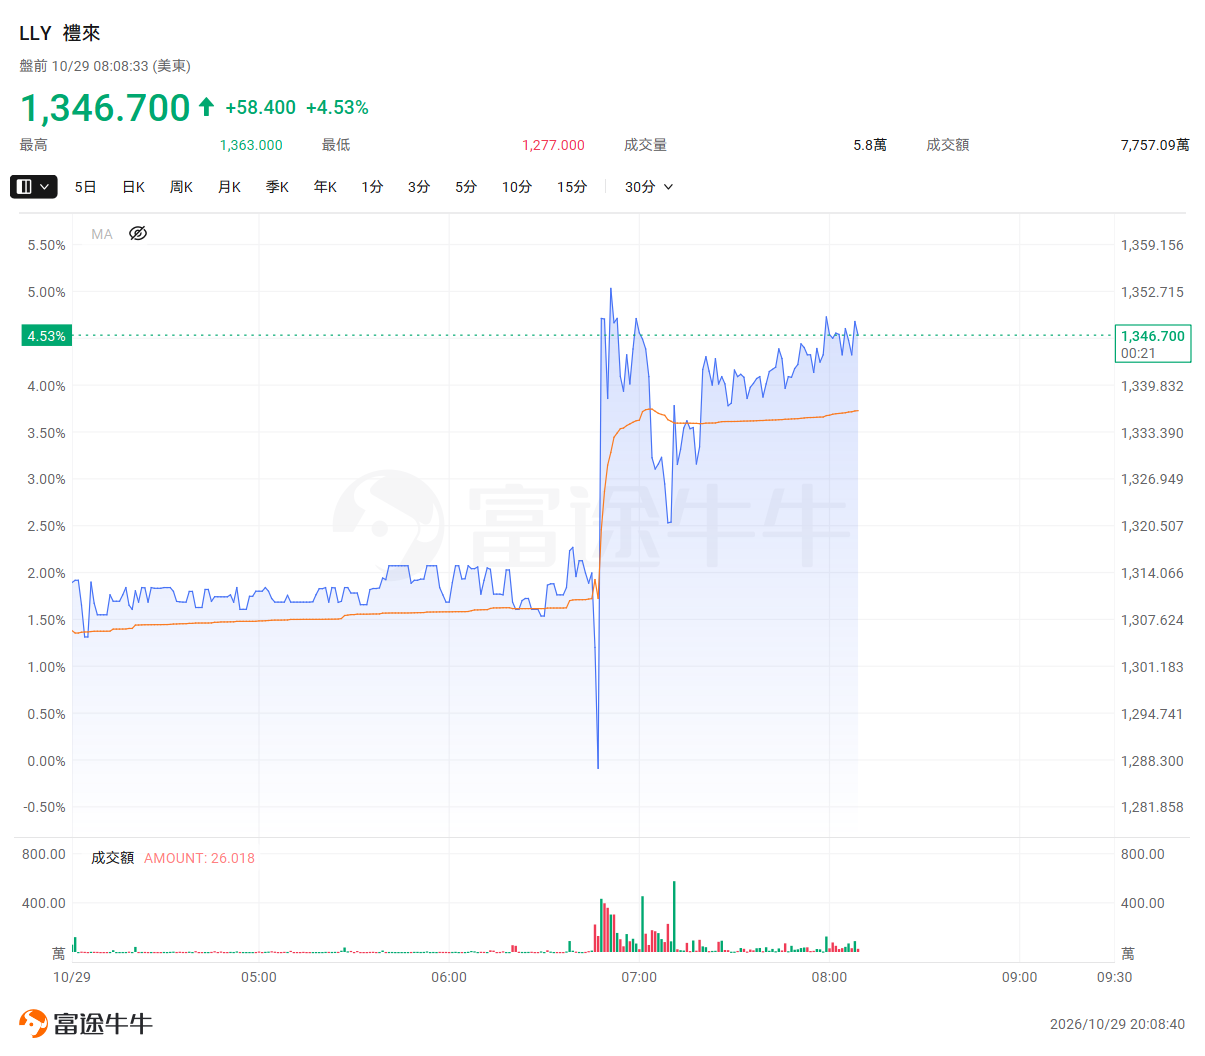
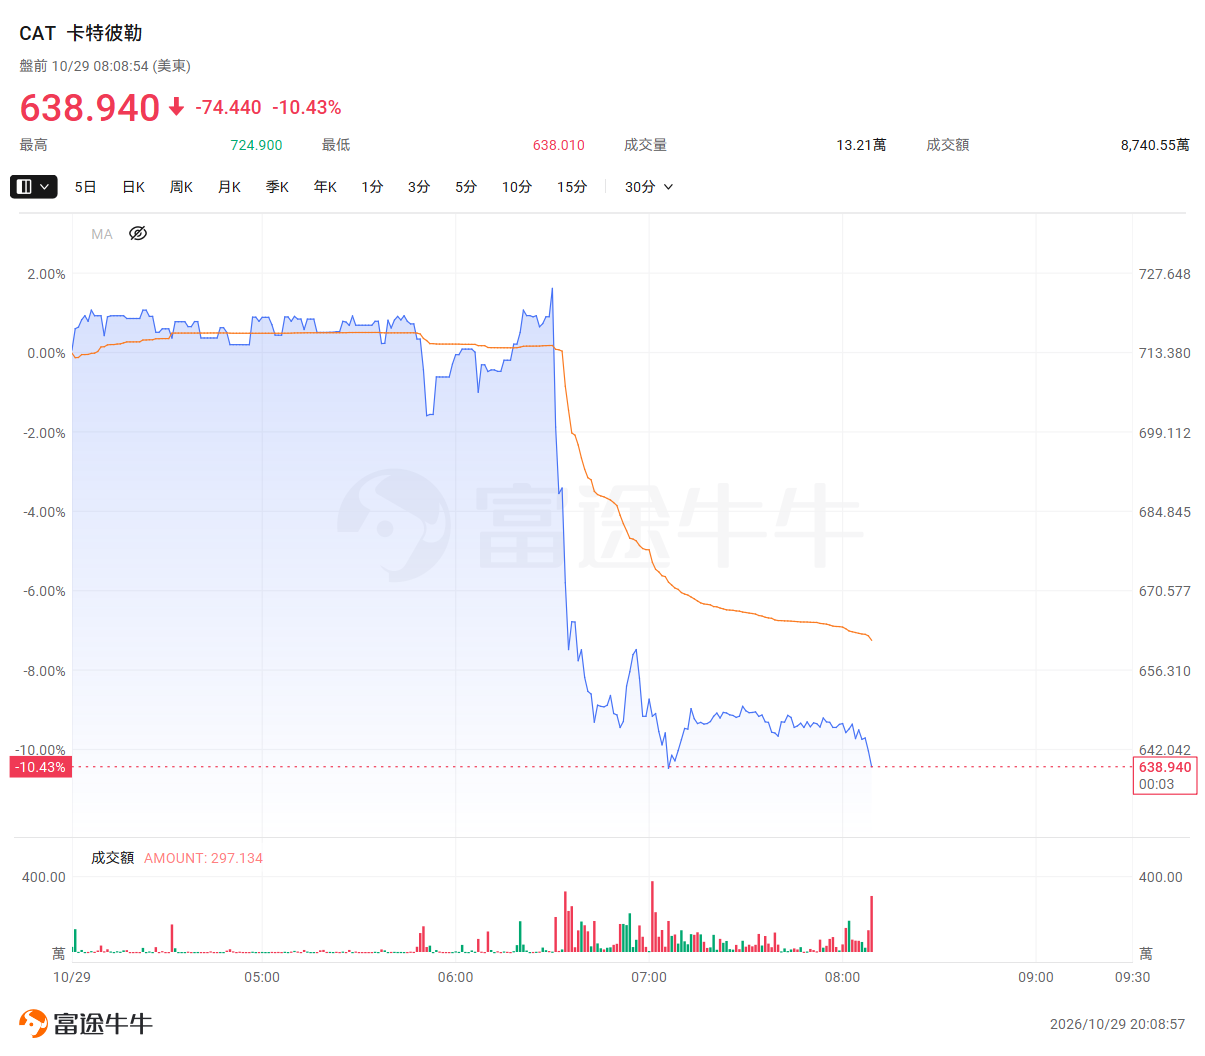
$Eli Lilly and Co (LLY.US)$Shares rose more than 4% after the earnings report, poised to open at an all-time high.$Caterpillar (CAT.US)$It fell more than 10% after the earnings report.
Individual Stock News
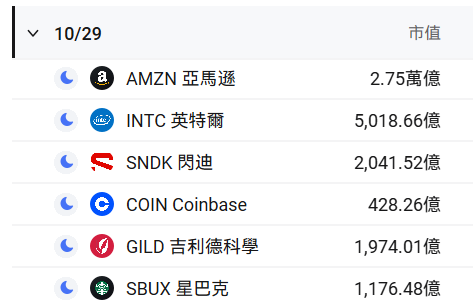
Amazon, Intel, and SanDisk face a major earnings test after the market closes tonight.
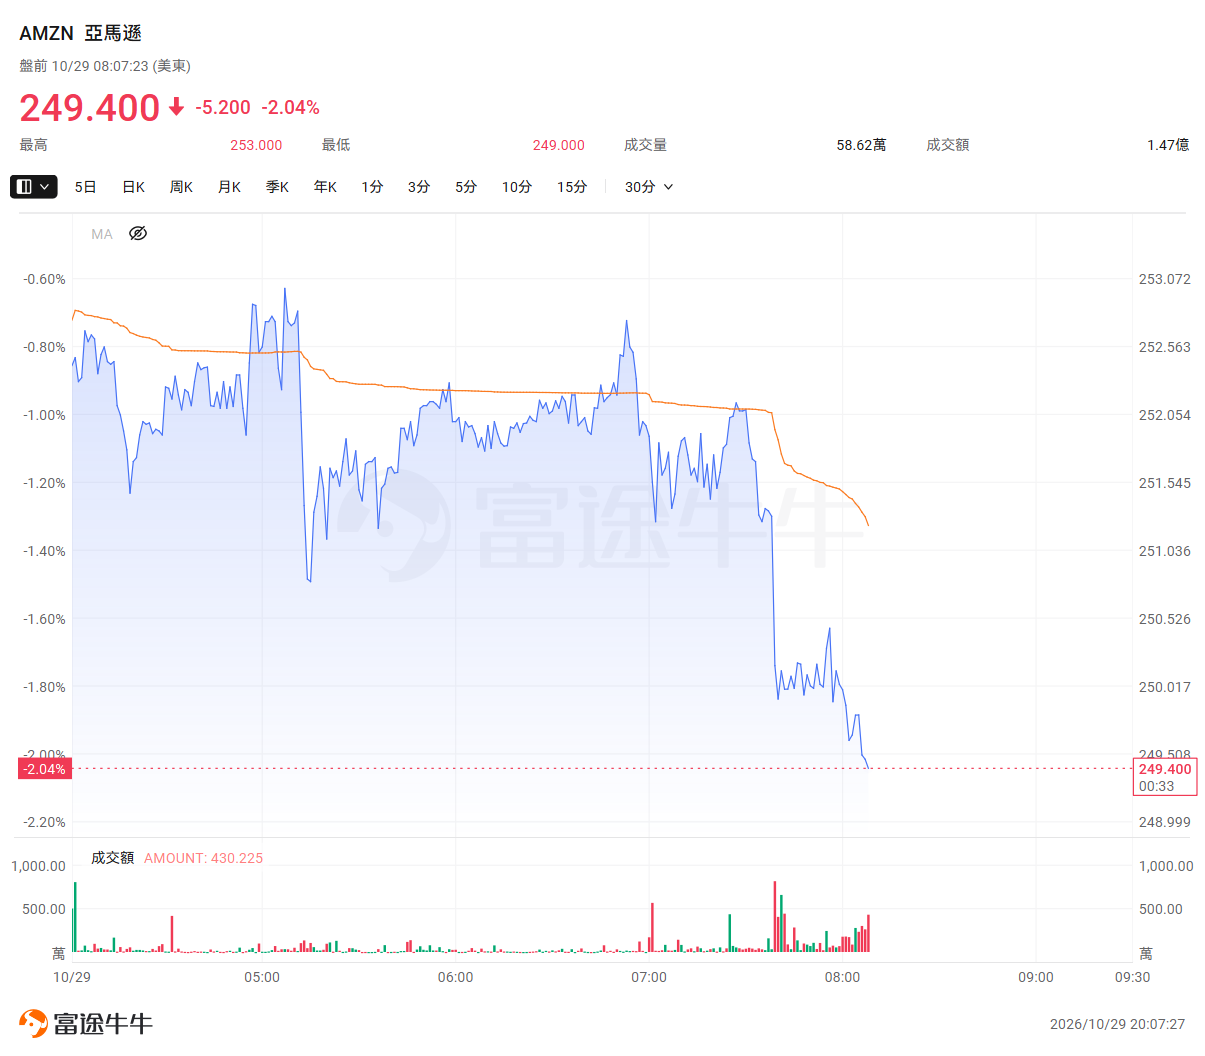
$Amazon (AMZN.US)$ 、 $Intel (INTC.US)$and$SanDisk (SNDK.US)$It will release its earnings report after the U.S. stock market closes today, covering the cloud computing, processor, and storage segments of the AI infrastructure value chain. For Amazon, the key question is whether AWS can sustain growth close to 40%; market expectations put revenue at around $202.2 billion and earnings per share at approximately $1.96. As for Intel, Bloomberg consensus forecasts revenue of about $16.5 billion, with foundry revenue around $6.1 billion; Bank of America expects its results may exceed expectations and has raised its guidance. SanDisk has accumulated a nearly 490% gain year-to-date, and investors will need to see storage supply-demand tensions genuinely translate into profitability. As of press time, Amazon was down more than 2% in pre-market trading, Intel fell over 3%, and SanDisk dropped nearly 3%.
NVIDIA launches new models and agent tools for RTX Spark.
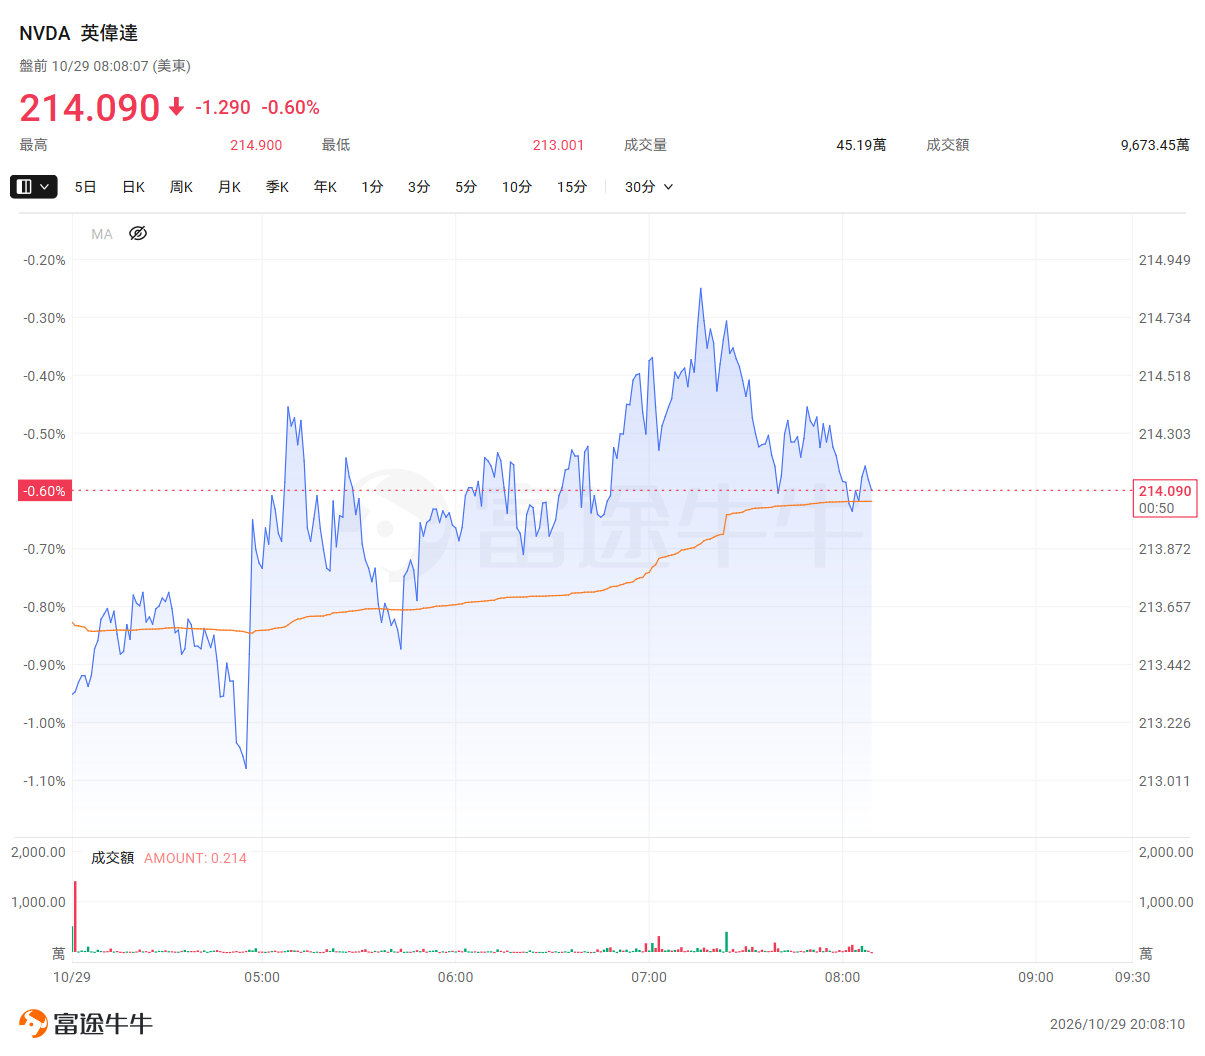
$NVIDIA (NVDA.US)$New models and agent‑tool support have been launched for RTX Spark Windows laptops. Among them, the Nemotron 3.5 Bolt E4B 4GB small model can run locally with as little as about 4 GB of memory, making it suitable for local voice assistants, game characters, and embedded interactions, and it supports 35 languages. Additionally, the Nemotron 3.5 Transcribe local quantized version, which supports speech transcription in 40 languages, will also be available on RTX Spark. As of press time, NVIDIA was slightly down in premarket trading.
Eli Lilly and Co. posted third-quarter results that far exceeded expectations, raising its full-year revenue guidance for the third time, and is poised to open at an all-time high.
$Eli Lilly and Co (LLY.US)$In the third quarter, revenue rose 39% year over year to $24.4 billion, surpassing the $22.61 billion forecast compiled by LSEG; adjusted earnings per share came in at $7.48, well above expectations. The company raised its full-year revenue guidance from $85–$87 billion to $91–$92 billion, marking the third upward revision this year. Tirzepatide remains the core growth driver, with Mounjaro sales up 65% to $10.72 billion and Zepbound up 49% to $5.35 billion—both exceeding estimates; oral weight-loss drug Founday's sales totaled $184 million, falling short of expectations. Based on pre-market quotes, Eli Lilly and Co. is poised to open at an all-time high. As of press time, the stock was up more than 4% in pre-market trading.
Caterpillar's third-quarter results exceeded expectations, with its data center segment driving a 30% increase in the power generation business.
$Caterpillar (CAT.US)$In the third quarter, sales and revenue rose 17% year over year to $20.68 billion, with adjusted earnings per share of $7.20—both exceeding Bloomberg consensus estimates; operating margin expanded from 17.3% to 20.4%. Sales in the Power & Energy segment increased 18% to $8.78 billion, with the power generation business up roughly 30%, driven primarily by gas turbines and large reciprocating engines used in data centers. At the end of the quarter, backlog stood at $78 billion, a 96% year-over-year increase. However, concerns about the sustainability of AI spending financed through debt weighed on the stock's performance. As of press time, Caterpillar was down 10% in pre-market trading.
Post-earnings sell-off at Google: It maintains its 2026 capital expenditure guidance and expects a "significant increase" in 2027, while JPMorgan and others have lowered their price targets.
$Google-C(GOOG.US)$Parent company Alphabet kept its 2026 capital expenditure guidance unchanged and expects a significant increase in capital spending in 2027; Reuters noted that disappointing search ad performance and accelerated AI investments have led to a sharp rise in cash burn, prompting the market to reassess the return cycle of AI spending. During the earnings call, CEO Sundar Pichai unveiled "the most advanced frontier model," Gemini 4 Carbon; management stated they will treat TPUs as a platform for external sales, with Meta, Anthropic, and Apple all using Google's TPUs. JPMorgan lowered its price target from $425 to $375, while MoffettNathanson cut theirs to $345. As of press time, Google was down 11% in pre-market trading.
Microsoft expects Azure's growth rate to accelerate further this fiscal quarter and has launched its first bond issuance since 2017, raising at least $25 billion.
$Microsoft (MSFT.US)$Azure revenue is expected to grow 49%–50% at constant currency in the second fiscal quarter, accelerating further from last quarter's 48%; total revenue for the second fiscal quarter is forecast at $96.0 billion–$97.1 billion. Microsoft projects capital expenditures exceeding $50 billion in the second fiscal quarter and approximately $170 billion for the full calendar year, with positive free cash flow expected to continue through fiscal year 2027. In addition, Microsoft is undertaking its first high‑yield U.S. dollar bond issuance in more than nine years, planning to raise at least $25 billion across 10 tranches with maturities ranging from 2 to 40 years. These proceeds will primarily fund the substantial capital spending required by the AI investment boom. The bond offering is led by Wells Fargo & Co, JPMorgan, and UBS Group, marking a significant step as major tech companies accelerate efforts to bolster their financial reserves in the AI infrastructure race.
The report says Marvell Technology is in talks to acquire Lumentum, with the deal potentially announced as early as next week.
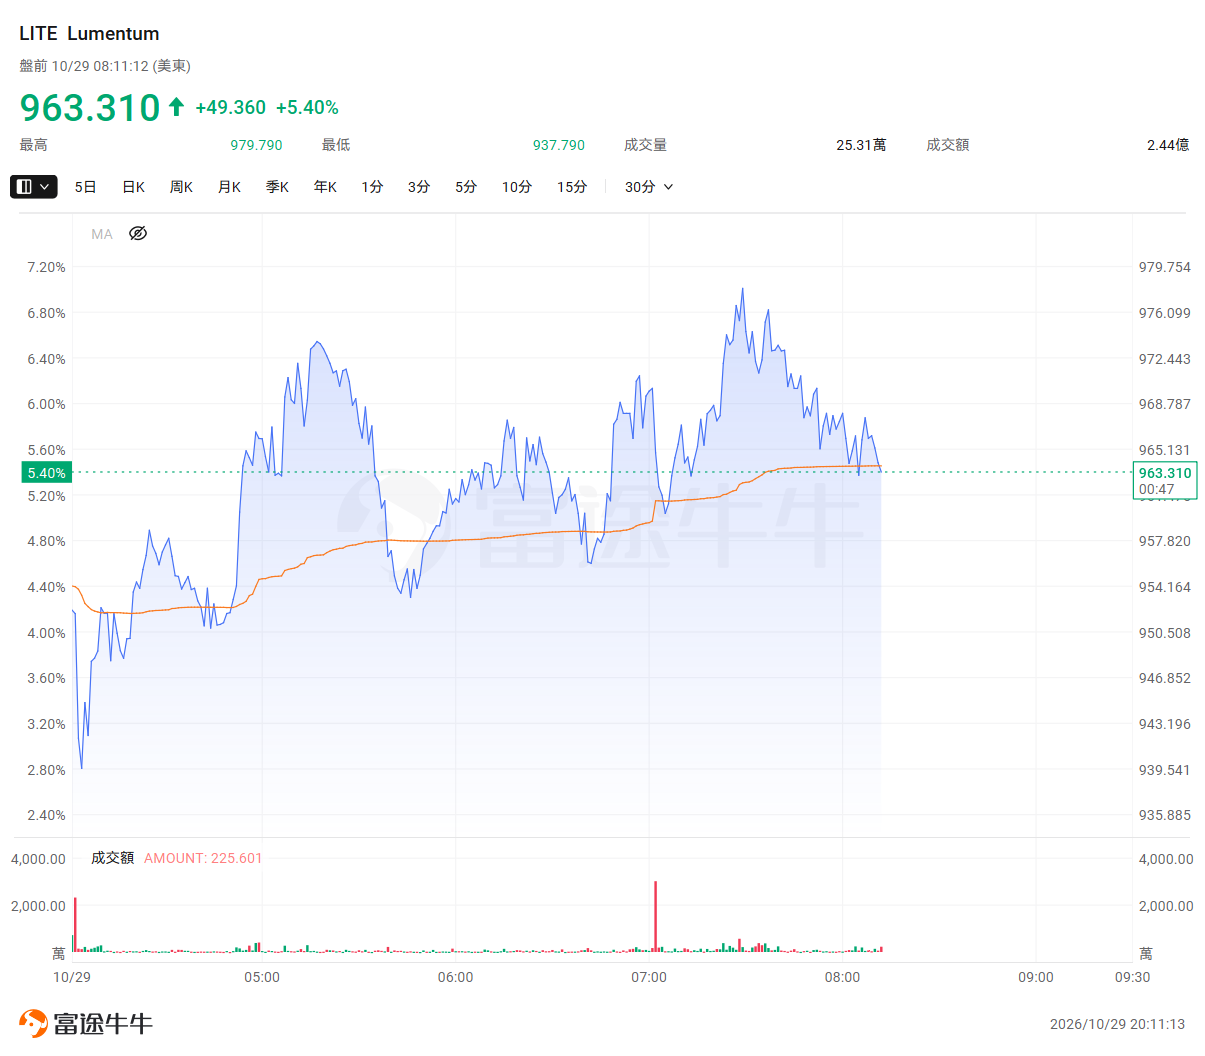
According to Bloomberg, citing sources familiar with the matter, Marvell Technology is in advanced negotiations to acquire data-center optical module manufacturer Lumentum, potentially completing a major M&A deal in the AI hardware supply chain. The transaction could be announced as early as next week. Reports indicate that Lumentum currently has a market capitalization of approximately $83 billion, while Marvell Technology's market cap stands at around $221 billion. At present, neither party has made an official announcement regarding the deal. As of press time,$Marvell Technology (MRVL.US)$Down 12% in pre-market trading,$Lumentum(LITE.US)$It rose more than 5% in pre-market trading.
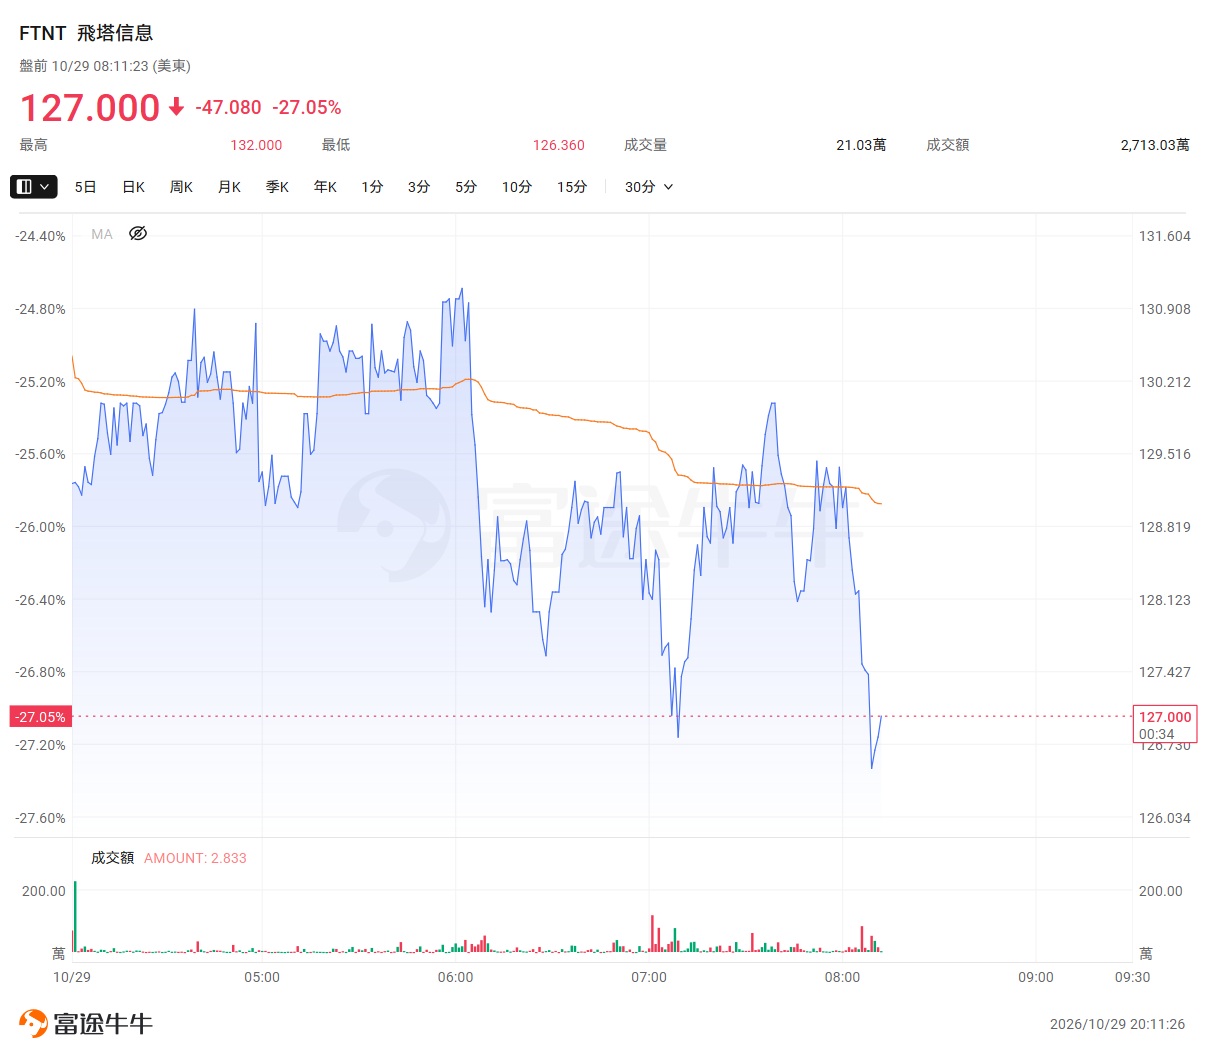
Fortinet plunges after earnings: product growth slows, service revenue guidance cut, and cybersecurity stocks come under collective pressure.
$Fortinet (FTNT.US)$Third-quarter revenue came in at approximately $2.08 billion, beating expectations, but product revenue growth slowed from 52% in the previous quarter to 37%, while service revenue fell short of estimates, prompting a downward revision of the full-year service revenue guidance to $5.15–$5.17 billion. Wells Fargo & Co. analysts noted that this quarter's billings exceeded expectations by only about 2%, far below the roughly 11% seen in the second quarter, and that Fortinet's stock has doubled so far this year, leaving market expectations quite high. Management stated that service revenue growth in 2027 is expected to outpace that of 2026. Dragged down by these factors, cybersecurity stocks such as CrowdStrike and Palo Alto Networks all traded lower in pre-market trading. As of press time, Fortinet was plunging 27% in pre-market activity.
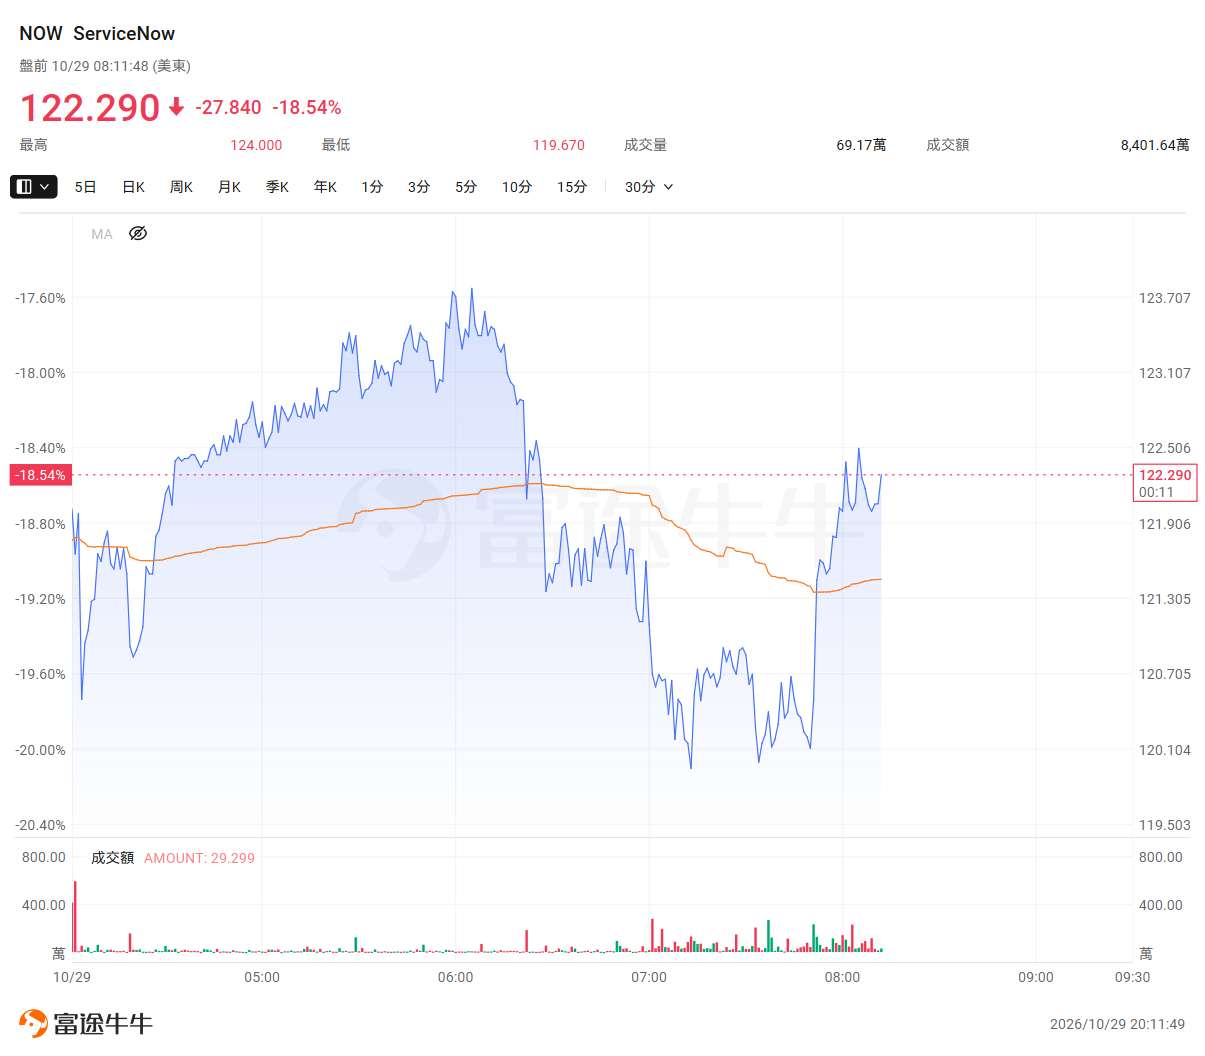
ServiceNow's cRPO guidance fell short of expectations, potentially marking the largest decline in its history.
$ServiceNow(NOW.US)$The fourth-quarter cRPO is expected to grow 18.5% at constant currency, below market expectations, which has been the main reason for the sharp drop in the stock price. During the earnings call, the CFO explained that the rising share of on-premises deployments and the exclusion of certain backlog orders from cRPO weighed on the metric. At the same time, the company raised its full-year free cash flow margin target from 35% to 36% and increased its 2026 AI annual contract value target to over $1.7 billion. According to MarketWatch, if the decline persists, ServiceNow would post its largest single-day drop on record. As of press time, ServiceNow was up 18% in pre-market trading.
Samsung's chip profits fell short of expectations, putting pressure on Micron in pre-market trading.
Reuters reported that,$Micron Technology (MU.US)$Pre-market trading is lower, weighed down primarily by the earnings report from South Korean rival Samsung Electronics.$Samsung Electronics (005930.KR)$Operating profit in the third quarter hit a record high, though semiconductor earnings fell slightly short of expectations, and the shareholder return plan has been postponed until January next year. Meanwhile, Samsung plans to increase its capital expenditures by roughly 60% and stated that its HBM products for 2027 are already sold out, with the company set to further expand sales of HBM, server DRAM, and SSDs.
Global Macro
The Federal Reserve has paused rate hikes to buy time, but it doesn't have much left.
This week, the Federal Reserve kept its benchmark interest rate unchanged at 3.75%–4%, but the vote was 10–2, with Board Governor Cook and Cleveland Fed President Mester advocating a 25-basis-point hike. The policy statement noted that the economy is expanding at a "strong pace" and that inflation remains elevated. At the press conference, Chair Powell said the Fed needs more data to assess the next steps in policy and favors a gradual approach, seeking to avoid overly tightening financial conditions before employment shows a clear deterioration. This pause appears aimed at buying time to gauge inflation's trajectory; however, if inflation fails to ease and labor market conditions do not weaken, the rationale for further waiting will grow increasingly tenuous. Following the meeting, investor expectations for a December rate hike edged higher.
U.S. PCE and GDP data are due tonight, putting Fed policy expectations to another test.
U.S. September PCE data and the third-quarter GDP preliminary estimate will be released at 8:30 p.m. Beijing time tonight. Whether inflation remains sticky and whether economic growth is slowing will be key tests of the Federal Reserve's policy outlook; any significant deviation from expectations could trigger volatility in U.S. Treasury yields, the dollar, and U.S. equities. TD Securities forecasts that third-quarter GDP growth will rise to 2.5%, underscoring the resilience of the U.S. economy and its ability to withstand further monetary tightening. Analysts note that the Fed has just signaled it needs "more information," with September's core PCE serving as the first critical benchmark; if the data come in hotter than expected, bets on a December rate hike could climb further.
With the U.S. midterm elections approaching, expectations for the 2028 presidential race have become a new market variable.
As the U.S. midterm elections enter their final stretch, prediction markets Polymarket and Kalshi indicate that the Democrats' implied probability of capturing both the Senate and the House exceeds 60%, with a greater than 90% chance of winning at least the House; the outcome of the Senate remains uncertain. If the Democrats gain control of both chambers, domestic legislation during Trump's remaining term could stall, with fiscal budgets, the debt ceiling, and regulation of AI data centers likely becoming key battlegrounds between the parties. According to Grisanti of MAI Capital, if the Republicans retain the Senate, the stock market may experience a brief rebound, but AI capital spending and corporate earnings will remain the more critical market drivers.
The report says the Trump administration is continuing negotiations on a temporary U.S.-Iran peace agreement.
According to Semafor, the Trump administration is continuing negotiations on a temporary U.S.-Iran peace agreement. Earlier, The Wall Street Journal reported that U.S. Vice President Pence had sent a letter to Rezaei, secretary of Iran's Supreme National Security Council, in an effort to break the deadlock in the talks; Trump acknowledged that he approved Pence's contact with Iran but said the letter primarily concerned providing medical supplies to Iran. Axios, citing U.S. officials, noted that Pence emphasized in his letter that any negotiations "must address the nuclear issue." However, analysts at Royal Bank of Canada Capital Markets believe that both the U.S. and Iran remain entrenched in their respective positions, and the overall trend still points toward a military escalation by the U.S. in the short term.
The banking sector has put on hold the issuance of a Texas data center bond linked to Anthropic.
According to Bloomberg, after Texas suspended approval of new projects due to concerns about grid risks, banks are delaying the sale of bonds—part of a $15 billion loan syndicated by Morgan Stanley—that were intended to finance Anthropic-related data centers. As a result, banks will have to keep this debt on their balance sheets for a longer period. Bloomberg data shows that cloud computing giants and data center developers have issued nearly $368 billion in debt this year, more than six times the amount from a year ago. Reuters notes that as borrowing costs rise, investors are growing concerned that AI spending fueled by debt will become harder to justify, leading to a cooling of market enthusiasm for AI-related deals this month.
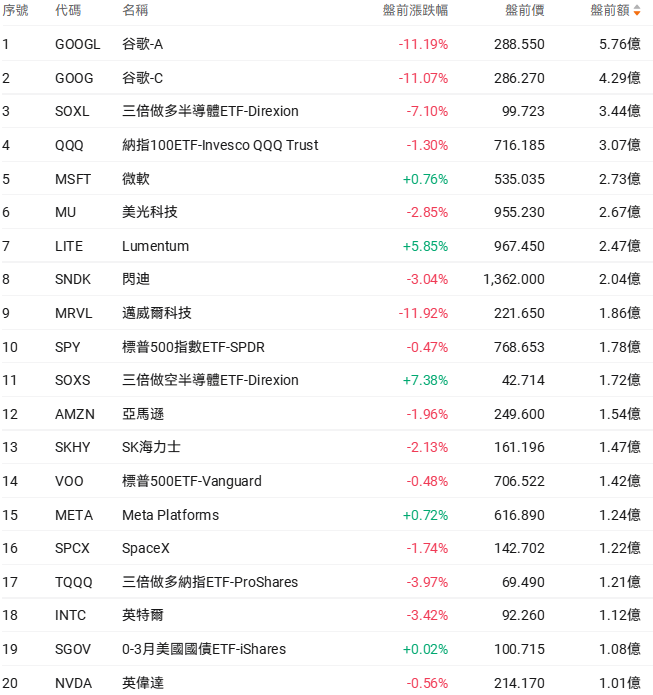
Top 20 Stocks by Pre-Market Trading Volume in the U.S. Market
U.S. Stock Market Macro Calendar Reminder
(The following is in Beijing Time)
21:15 The European Central Bank announces its interest rate decision.
21:45 ECB President Lagarde holds a press conference
22:30 U.S. EIA Natural Gas Inventories for the Week Ending October 23
After-hours earnings
 Want to pick stocks or analyze them? Curious about your portfolio's opportunities and risks? For all your investment questions,Just ask Futubull AI!
Editor/rocky