The primary focus of 23-hour trading is not to compete for listed companies, but to compete for trading orders. Nasdaq prioritizes securing orders before competing on price. Only after establishing pricing power can it attract more enterprises. The aim of 23-hour trading is to transform Asian daytime hours into the overnight session for U.S. stocks, thereby vying for global primacy in the initial pricing of assets.
The most active instruments during Asian trading hours are not technology stocks, but U.S. market ETFs.
On December 6, 2026, Nasdaq plans to launch stock trading for 23 hours a day, five days a week. The SEC has approved Nasdaq’s rule changes for 23/5 trading, but the official launch still depends on the readiness of market data infrastructure, such as the SIP, and the implementation of supporting regulations.
 The newly added night session runs from 9:00 p.m. to 4:00 a.m. the following day, Eastern Time. During December, under Standard Time, this corresponds to 10:00 a.m. to 5:00 p.m. Beijing Time, allowing Asian investors to trade U.S. equities directly during their daytime hours.
This reform appears to be merely an extension of trading hours, but it is fundamentally a battle for order flow. Nasdaq aims to recapture trading volume from night-session platforms, internal broker-dealer crossing systems, and other exchanges. It also seeks to ensure that global investors turn to the U.S. market first for execution following major events in any time zone.
In the short term, Nasdaq is competing for orders from ATS night-session platforms, internal broker crossing systems, and other exchanges. In the medium term, it is vying for nighttime price discovery for ETFs and large-cap technology stocks. In the long term, it is targeting the gateway to global asset pricing during Asian daytime hours.
Nasdaq’s extension of trading hours is not intended to encourage U.S. investors to stay up late trading stocks. Rather, it aims to convert the daytime hours of Asian investors into trading hours for U.S. equities.
Asian daytime becomes the night session for U.S. equities.
The core trading session for U.S. equities lasts only six and a half hours. Pre-market and after-hours trading have long existed. Nasdaq’s new arrangement fills the gap between 9:00 p.m. and 4:00 a.m. the following day, Eastern Time, leaving only one hour daily for maintenance.
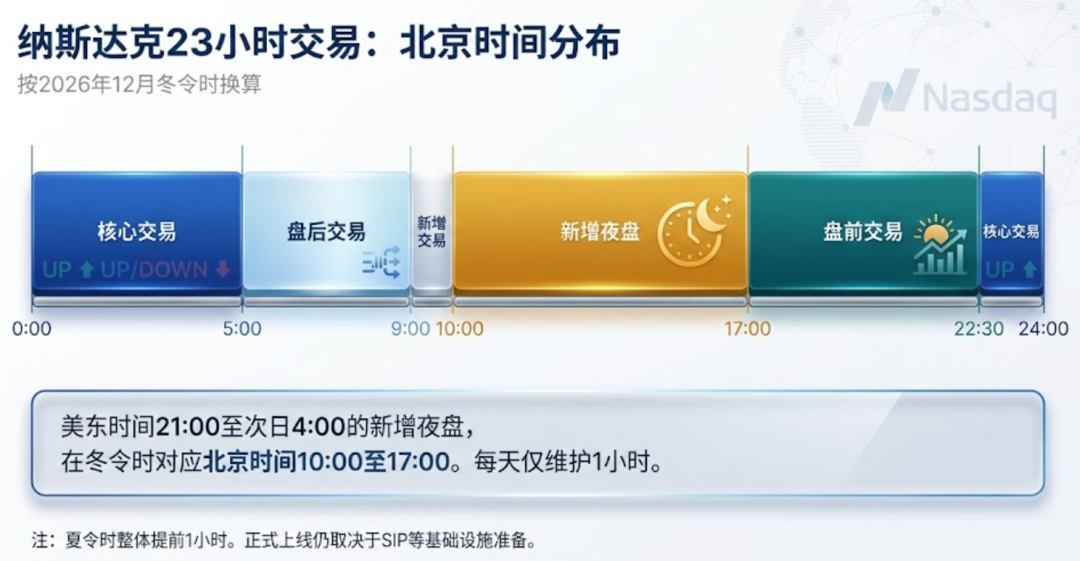
This newly added trading window aligns perfectly with daytime hours in major Asian markets. Investors in China, Japan, and South Korea no longer need to wait until late at night. Furthermore, Asian capital does not have to wait for the New York market open following developments such as Federal Reserve policy announcements, geopolitical conflicts, or corporate news releases.
What Are Investors Buying During the Asian Session?
Nasdaq has released a set of U.S. overnight trading data covering the period from January to June 2025. These transactions occurred primarily during the Asian session. The data does not identify investor nationality, nor can all trades be attributed solely to Asian capital. Instead, the data is more suitable for analyzing trading preferences and instrument selection during the Asian session.
The U.S. market comprises approximately 11,300 tickers. Only 1,403 saw overnight trading activity, and just 644 recorded daily turnover exceeding $10,000. The top 15 instruments accounted for approximately 53% of total overnight volume, a figure Nasdaq summarizes as nearly 55%. Among these, 12 were ETFs, while only three were individual stocks. This indicates that overnight trading does not represent a broad migration of market liquidity, but rather concentrated trading in a few macro-risk instruments and mega-cap assets.
SPY, IVV, and VOO, all S&P 500 ETFs, collectively accounted for 25.6% of overnight trading volume. QQQ accounted for 4.5%. TQQQ (3x Long QQQ) and SQQQ (3x Short QQQ) together accounted for 2.9%.
The three most actively traded individual stocks were Tesla, NVIDIA, and Alibaba, collectively accounting for 12.7% of volume. Other active instruments included gold, Indian equities, international equities, and corporate bond ETFs.
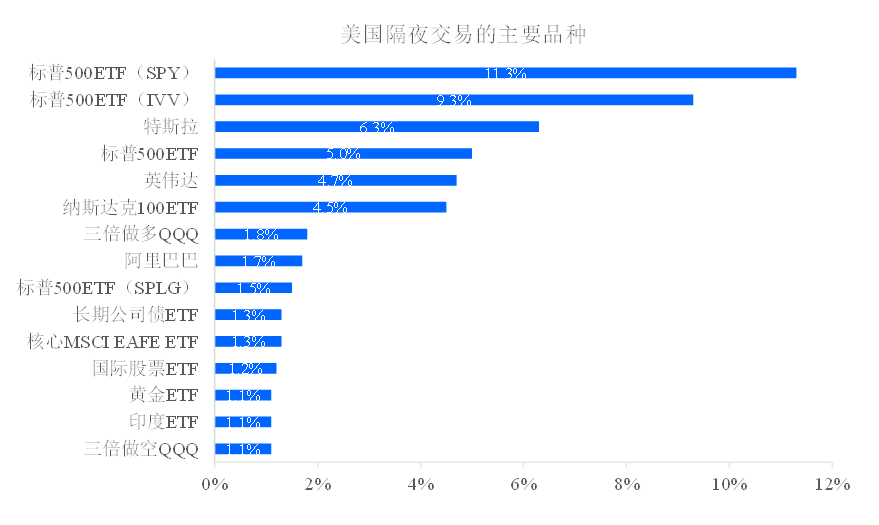
Investors in the Asian session prioritize trading the U.S. market over trading specific U.S. companies. The focus of overnight trading is not on company-specific research, but on risk management.
Nasdaq's primary objective is to capture order flow.
SPY, IVV, VOO, and Alibaba are not listed on Nasdaq. Nevertheless, they can still be traded on the platform. This fact illustrates that the primary focus of 23-hour trading is not to compete for listed companies, but to compete for order flow.
After U.S. exchanges close, orders do not disappear; they flow to overnight platforms such as Blue Ocean, internal broker-dealer systems, and other trading venues. The New York Stock Exchange and Cboe are also advancing extended trading hours. The London Stock Exchange is preparing to build a new extended-hours trading platform, starting with ETFs. Proponents argue that bringing these orders back to regulated exchanges can enhance trade transparency, quote visibility, and market surveillance capabilities.
Exchange revenue is not derived solely from transaction fees. Order flow generates market data revenue, attracts market makers, and helps form reference prices. Whoever captures the order flow first incorporates information into prices earlier.
Extended trading hours will also enhance the attractiveness of U.S. markets to overseas companies, although this effect is secondary to the competition for order flow. When choosing a listing venue, companies still compare valuations, liquidity, investor structure, and regulatory costs.
Nasdaq prioritizes capturing order flow before competing on pricing. Only after securing price discovery can it attract more companies.
Who pays for 23-hour trading?
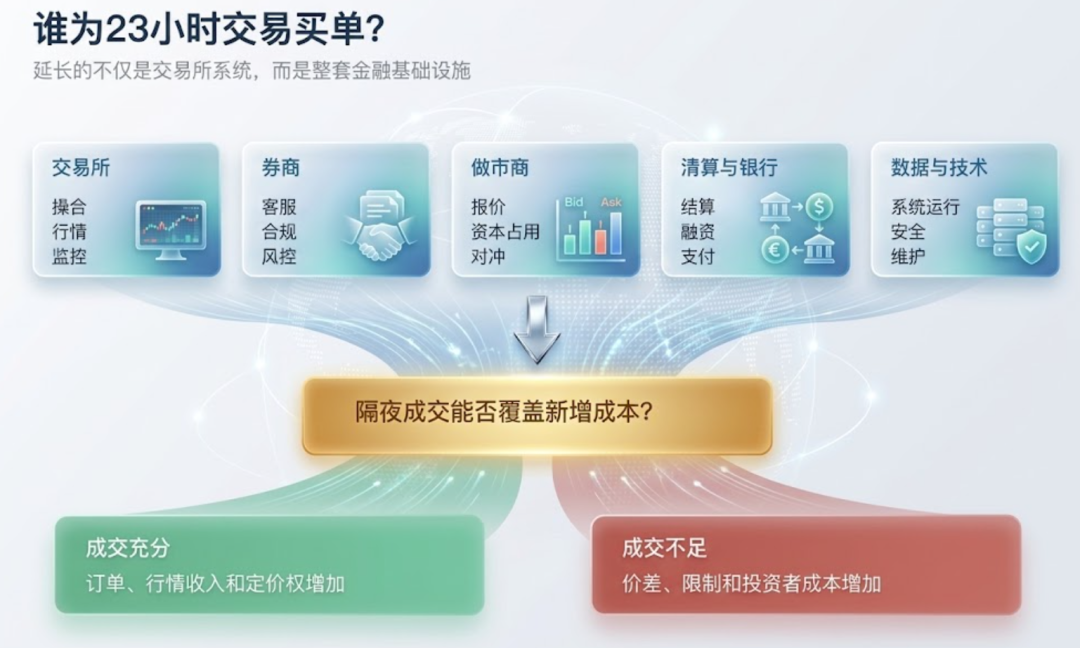
Exchanges are extending more than just their matching systems; the entire financial infrastructure must operate for longer hours.
Exchanges need to continuously provide market data and monitor trading. Broker-dealers must arrange customer service, compliance, and risk control. Market makers must extend quoting hours, tying up more capital. Clearing houses, banks, data vendors, and technology providers must also operate in sync. System maintenance windows are compressed, leading to increased cybersecurity risks.
Existing pre-market and after-hours trading already bears part of the cost. Adding overnight sessions will still increase expenses related to personnel, systems, capital, and compliance. The issue is that overnight trading volume for most stocks is very thin. A large number of institutions must maintain full-service operations for a small number of ETFs and large-cap technology stocks.
Costs will ultimately be passed on to investors. This may not necessarily appear as a specific overnight commission. Bid-ask spreads may widen. Financing costs may rise. Broker-dealers may restrict market orders and eligible securities. Market makers will also factor in capital usage and hedging risks into their quotes.
What the exchange extends is trading hours; what investors bear is the bid-ask spread. Trading time is not a free public service but a financial product whose costs are covered by trading volume.
Faster price discovery does not equate to greater price accuracy.
While 23-hour trading enhances market responsiveness, it does not automatically create liquidity.
With fewer overnight participants and insufficient market depth, trading hours for stocks, futures, and options are not fully synchronized. Market makers who sell stocks may not be able to immediately hedge using other instruments, leading to more conservative quoting and wider spreads.
Following major news events, prices form rapidly during the night session. These prices may reflect new information or merely result from limited order flow. Once the main trading session begins and more institutional participants enter, night-session prices often require re-evaluation.
Investors gain the freedom to trade at any time, but also the freedom to make mistakes at any time. The night session is better suited for mitigating sudden risks rather than chasing short-term price movements. Limit orders are more important than market orders. Waiting for liquidity to recover can sometimes be less costly than immediate action.
23-hour trading addresses the question of "whether one can sell," but not "at what price one should sell."
The United States exports not only capital but also pricing power.
ETFs dominate overnight trading volume, revealing deeper structural shifts. Global investors can trade U.S. equities, as well as gold, Indian equities, global bonds, and other countries' market risks, through U.S. markets. While these assets may not belong to the United States, trading and pricing are increasingly concentrated there. Following major events, global capital first adjusts positions via U.S. ETFs. Even before local markets open, the U.S. market has already established reference prices.
This raises questions for Asian markets. When Indian equities are traded via U.S. ETFs, who determines the international price of Indian assets? For Chinese tech stocks listed in both Hong Kong and the United States, which market reflects global expectations earlier? When Asian markets open, do they price independently, or do they correct the answers already provided by the U.S. market?
The United States exports not only capital but also price levels.
Should the Hong Kong Stock Exchange replicate Nasdaq?
The Hong Kong Stock Exchange (HKEX) has already studied extending trading hours. Discussions in the cash market have included a 9:00 AM opening and the elimination of the lunch break. The current focus remains on extending nighttime trading for derivatives. In the short term, it is more appropriate for Hong Kong stocks to pilot limited extensions and specific product expansions rather than directly replicating a 23-hour cash trading schedule.
The Stock Connect program represents the primary constraint. Southbound capital accounts for a significant proportion of trading volume in Hong Kong stocks. If HKEX were to open nighttime trading sessions independently, mainland Chinese funds would be unable to participate synchronously. This could fragment trading into two separate markets. While operational costs for financial institutions would inevitably rise, there is no guarantee of new order flow. A more realistic path is to pursue incremental growth by focusing on derivative nighttime trading, ETFs, a select few large dual-listed stocks, and facilities for RMB trading and settlement.
Hong Kong’s true advantage does not lie in its operating hours. Hong Kong offers global investors direct access to Chinese internet, consumer, pharmaceutical, and artificial intelligence companies that are unavailable in other markets. The more critical task for HKEX is to increase the supply of high-quality assets, expand cross-boundary connectivity, and improve RMB trading and settlement mechanisms.
Nasdaq brings global orders to the U.S. market, while HKEX brings Chinese assets to global investors. The two compete for pricing power, but their paths differ.
Conclusion: It is not about who keeps the doors open longer
While 23-hour trading appears to be a change in trading rules, it fundamentally reflects competition among trading platforms, financial intermediaries, and major capital markets for global order flow.
Trading hours serve merely as an amplifier. Where there is global demand, extended hours can boost trading volume and expand pricing power. Without sufficient demand, extended hours will only increase costs and fragment liquidity.
Without assets worthy of sustained trading by global investors, extending operating hours will only prolong periods of thin trading. The true competition among exchanges is not about who stays open longer, but about who defines the next global price.
Editor/lambor