$S&P 500 Index (.SPX.US)$Rose 0.47% to close at 7,667.45 points,$Nasdaq Composite Index (.IXIC.US)$Rose 0.45%, while the Dow Jones Industrial Average gained 0.56%. Brent crude settled at $95.63, up 1.04%.$Dell Technologies (DELL.US)$Driven by a record 15.76% surge in AI server orders,$Broadcom (AVGO.US)$Reported AI chip revenue surged 221%, with shares initially falling before rising in after-hours trading. The yield on UK 10-year gilts climbed to its highest level since August 2007.
Oil prices retreated from intraday highs, pausing their rally, which subsequently cooled inflation expectations.$US 10-Year Treasury Yield (US10Y.BD)$Retreating from intraday highs, the three major U.S. stock indices staged a modest rebound to close higher, ending a three-day losing streak.
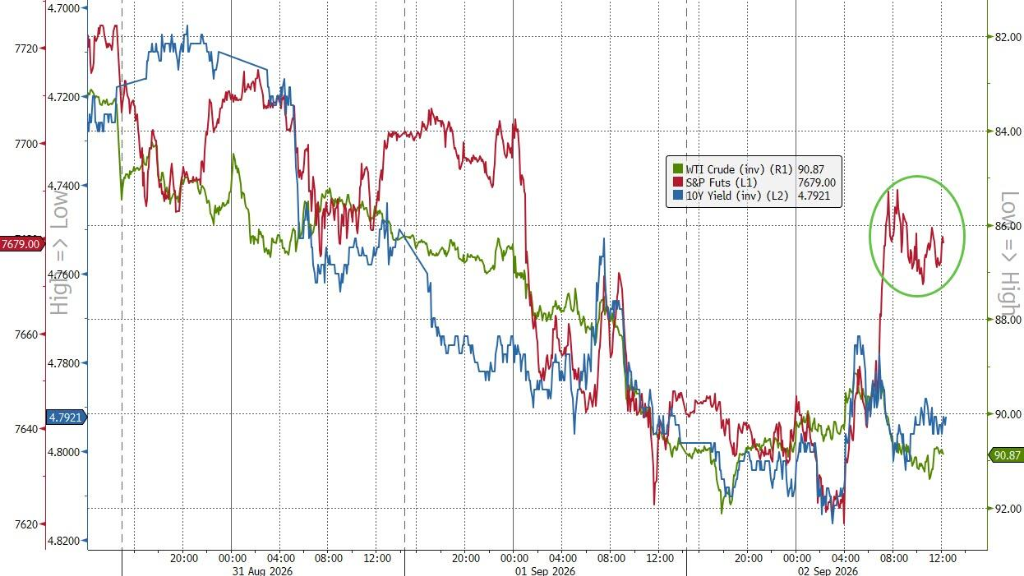
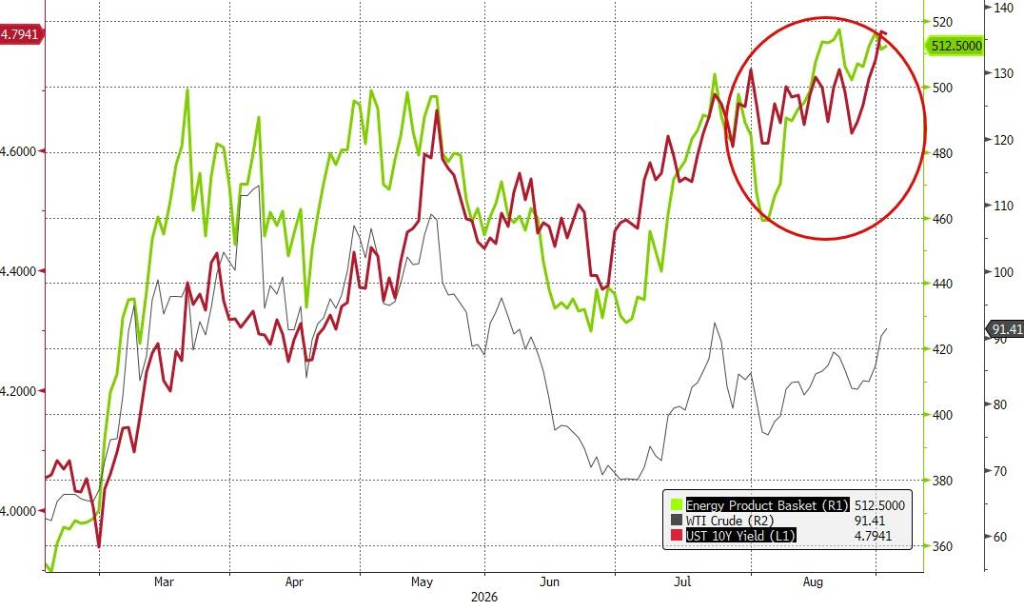
WTI crude oil touched an intraday high of $92.28, reaching a five-week high, before turning negative during the session. It recovered most of its losses by the close, ending up 0.88%. Brent crude settled at $95.63, rising 1.04%.
 By market capitalization, as of the close of trading,NVIDIA (NVDA.US)Rose 3.21%, Apple fell 0.05%,$Google-A (GOOGL.US)$Rose 0.63%,$Microsoft (MSFT.US)$Fell 0.84%,$Amazon (AMZN.US)$Rose 0.02%,$Taiwan Semiconductor (TSM.US)$up 0.36%,$SpaceX (SPCX.US)$down 1.07%, Broadcom down 0.66%, Meta up 2.47%,$Tesla (TSLA.US)$up 0.26%,$SK Hynix (SKHY.US)$up 2.61%,Eli Lilly and Co (LLY.US),up 0.01%, Berkshire Hathaway Class A up 0.85%.
At the individual stock level, AI hardware and AI software sectors diverged. Dell Technologies soared 15.76% on record AI server orders, while Credo Technology plunged 20.04% due to shrinking gross margins. Cybersecurity stocks collectively declined under the shadow of OpenAI's new products.
Well-known "defense AI" concept stock$Palantir (PLTR.US)$closed down 5.81%. Tech giant Google released its cybersecurity model, Gemini 1.5 Flash Cyber, on Wednesday, entering the government and defense AI sector where Palantir is heavily reliant.
$Nasdaq Golden Dragon China Index (.HXC.US)$closed down 0.05% on Wednesday. As of the close,$Alibaba (BABA.US)$down 0.92%,$PDD Holdings (PDD.US)$down 1.11%,$NetEase (NTES.US)$down 0.5%, JD.com down 0.25%,Baidudown 0.55%, Trip.com down 0.48%,$Li Auto(LI.US)$up 0.92%,$Bilibili (BILI.US)$down 2.15%,$Nio (NIO.US)$down 4.93%; the company had previously received a warning from the exchange due to its share price remaining below $1 for an extended period$Viomi Technology (VIOT.US)$surged 83.64%.
Cracks in the European bond market remain unhealed, with the yield on the UK 10-year gilt hitting its highest level since August 2007. The yield on the 10-year German bund rose more than 17 basis points over six days, reaching a new high since 2011.
Oil prices retreat from highs, pausing the rally
WTI crude touched an intraday high of $92.29 overnight before giving up gains. Rumors regarding agreements related to Venezuela triggered profit-taking, with the intraday low seen at $88.97.
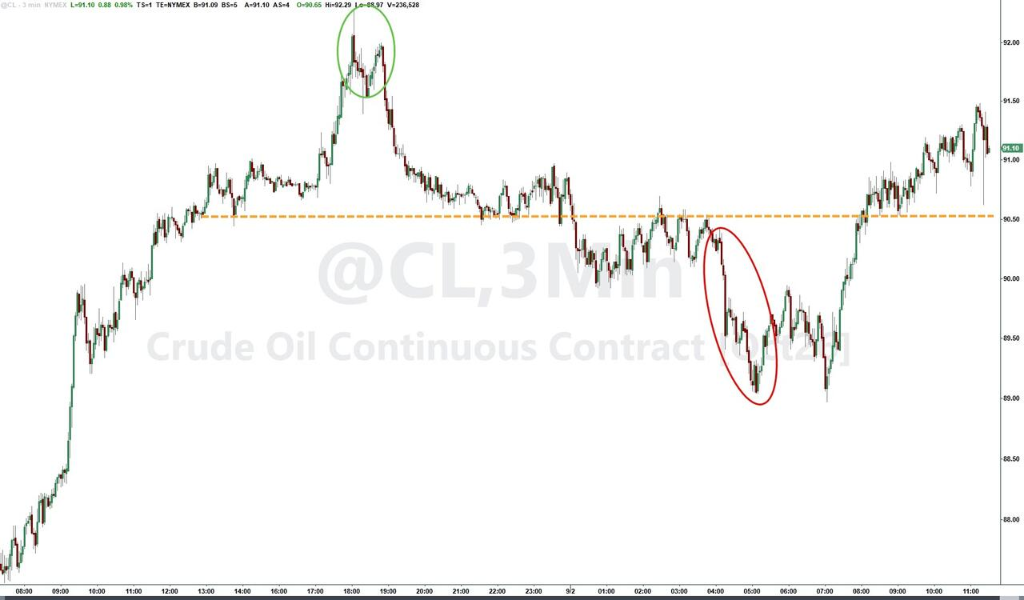
According to CCTV, on September 2, Venezuelan Acting President Rodriguez met with U.S. Energy Secretary Wright. Following the meeting, the two countries formally signed multiple cooperation agreements. It is reported that the Venezuelan government and U.S.$Chevron (CVX.US)$oil companies and other enterprises signed agreements on oil expansion projects.
As the geopolitical premium faded, oil prices gradually recovered during the U.S. trading session, settling at $91.01 per barrel. Brent crude reached an intraday high of $97.04, also its highest level since July 24.
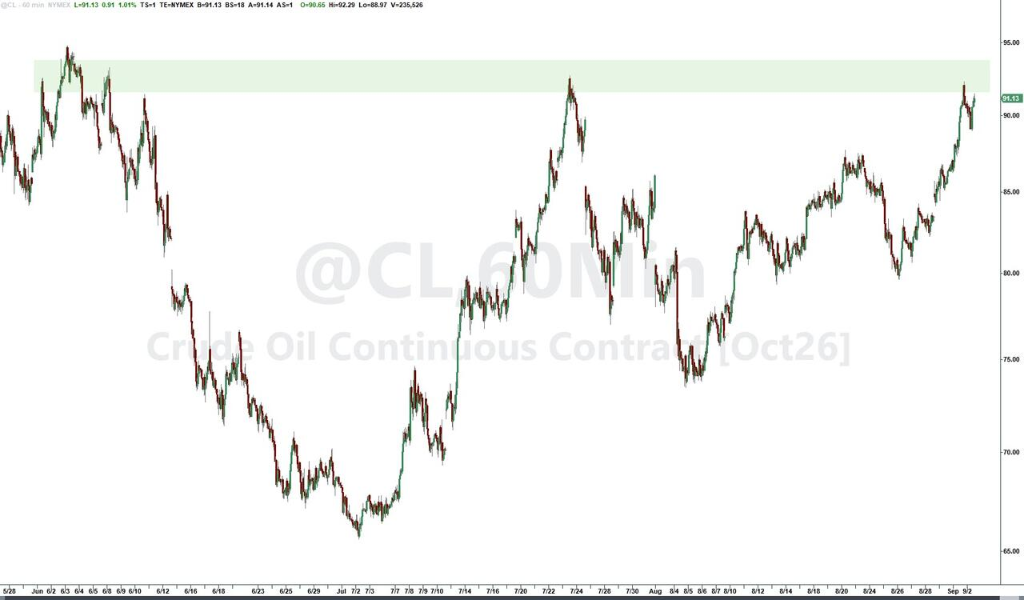
Data released by the U.S. Energy Information Administration (EIA) on the day showed that U.S. commercial crude oil inventories fell by 4.5 million barrels to 424.5 million barrels for the week ended August 28, a decline far exceeding analysts' expectations of a 1.1 million-barrel draw. Refinery utilization rates rose by 0.6 percentage points to 98%, the highest level since August 2018, while daily crude processing volumes increased by 103,000 barrels.
High refinery utilization rates simultaneously weighed on refined product prices. RBOB gasoline futures fell 1.06%, and heating oil dropped 0.14%, marking a divergence between crude oil and refined products. Calculated at 42 gallons per barrel, the premium of heating oil over WTI narrowed by $1.66 to $105.27, while the gasoline premium narrowed by $2.49 to $39.38.
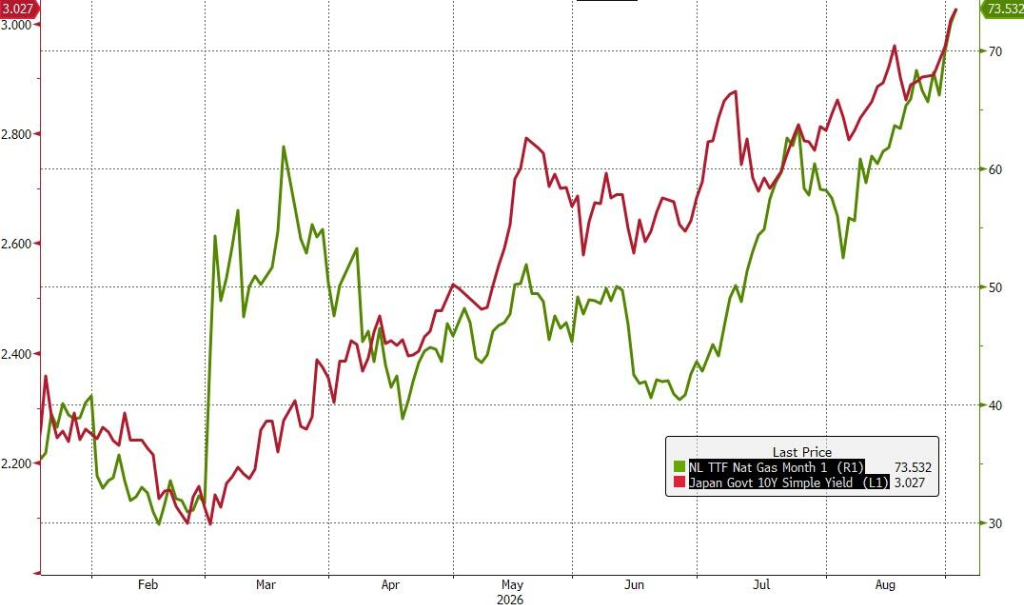
European natural gas futures rose to their highest level since 2023.
Ole Hansen, commodity strategist at Saxo Bank, stated that the pullback in oil prices from their five-week highs has supported market risk appetite.
Energy stocks continued their upward trend.$Halliburton (HAL.US)$up 2.26%,$Schlumberger (SLB.US)$up 1.71%,$Phillips 66(PSX.US)$up 1.61%,$Marathon Petroleum (MPC.US)$up 1.04%,$ConocoPhillips (COP.US)$up 0.74%,$Exxon Mobil (XOM.US)$down 0.23%.
Chevron announced plans to invest over $7 billion in Venezuela over the next five years, targeting a daily production capacity of approximately 600,000 barrels, thereby adding an incremental source to medium- and long-term supply.
Dell orders hit record highs as AI hardware stocks rally collectively
On September 2, New York time, U.S. stocks ended a three-day losing streak. The S&P 500 Index rose 0.47% to close at 7,667.45 points, the Nasdaq Composite Index gained 0.45%, and the Dow Jones Industrial Average advanced 0.56%.
Notably, the S&P 500 Index has not recorded a single-day decline of more than 1% for 24 consecutive trading sessions. The last time such prolonged calm was observed was in mid-May.
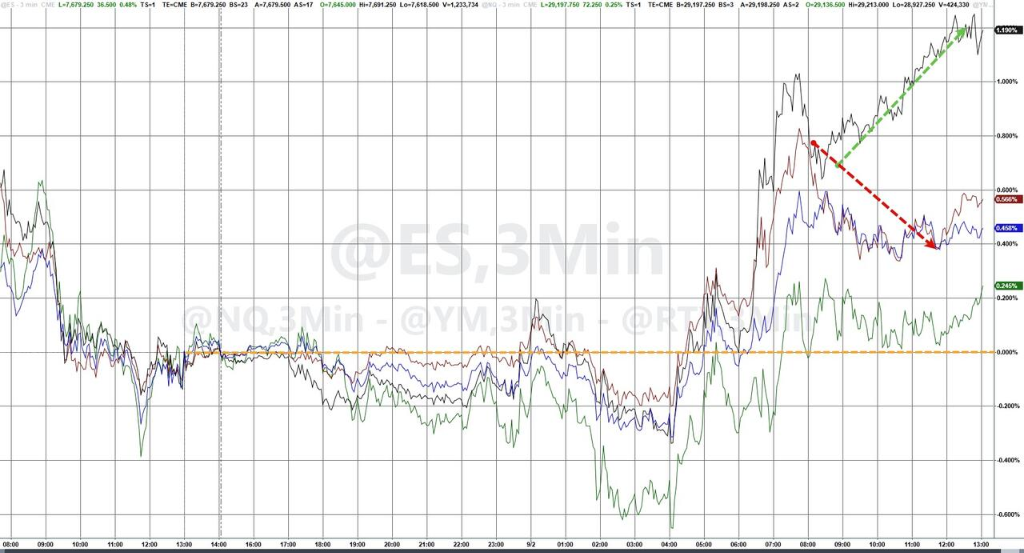
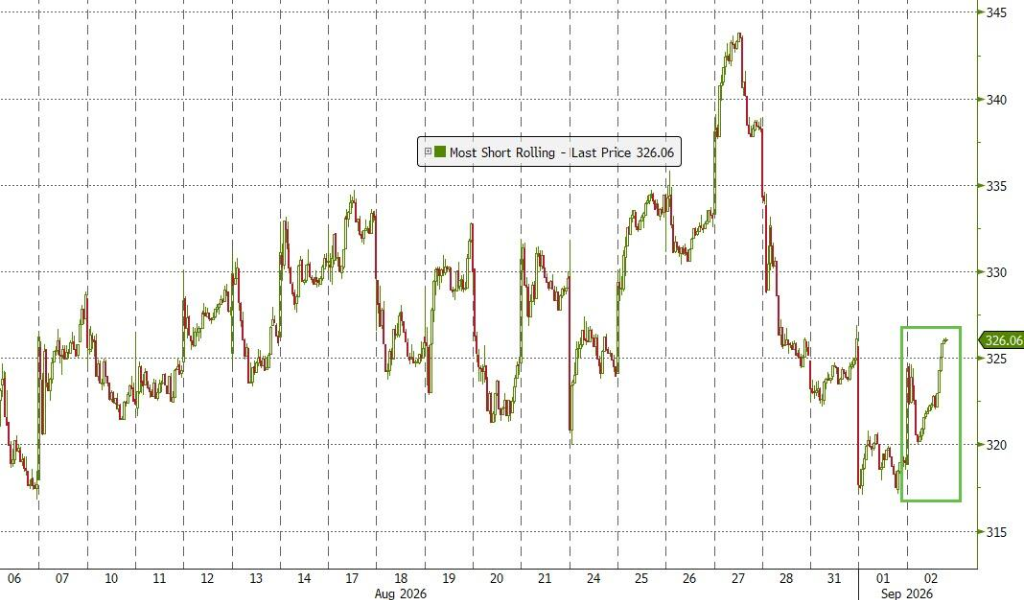
$Russell 2000 Index (.RUT.US)$up 1.13%, leading the four major indices and recording the second-largest short squeeze of the month. The direct driver of this rally was the forced covering of short positions in small-cap stocks.
In terms of individual stocks, Dell Technologies announcedstrong financial resultsafter the market close yesterday. Its stock price surged 15.76% on Wednesday, closing above $492.
Full-year guidance was the core of this earnings report. Dell raised its revenue target to $192 billion, significantly exceeding the consensus analyst estimate of $173.76 billion. Management's confidence stems from its AI server business, where order volumes have reached record highs for the company.
The AI hardware supply chain strengthened overall. NVIDIA rose 3.20%,$Micron Technology (MU.US)$up 2.43%,$Gitlab (GTLB.US)$up 9.98%. Broadcom closed slightly lower by 0.66%, with market focus shifting to its earnings report released after hours.
After hours, Broadcom reported third-quarter revenue of $29.6 billion, an 86% year-over-year increase, including $16.7 billion from AI chip sales, up 221% year-over-year. Guidance for the fourth quarter projects revenue of $34.8 billion and AI chip revenue of $21.7 billion, representing a 236% growth rate.
Cybersecurity stocks plunged, putting pressure on AI software valuations.
Overall performance in the artificial intelligence sector remained lackluster today, underperforming the S&P 500 Index.
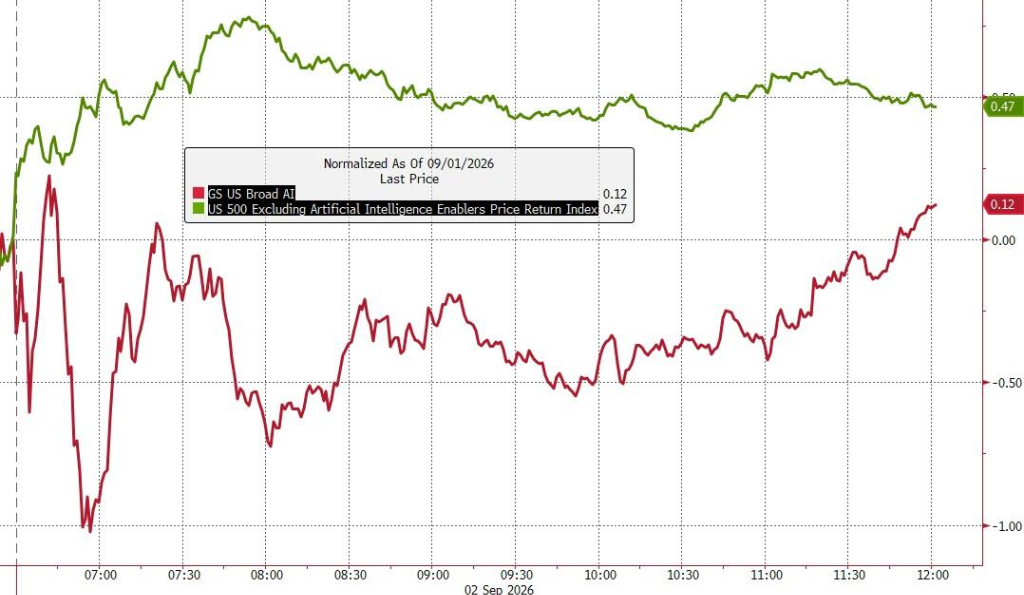
Performance among leading companies in the AI sector was mixed; the semiconductor industry stood out, while software infrastructure and agentic AI lagged behind.
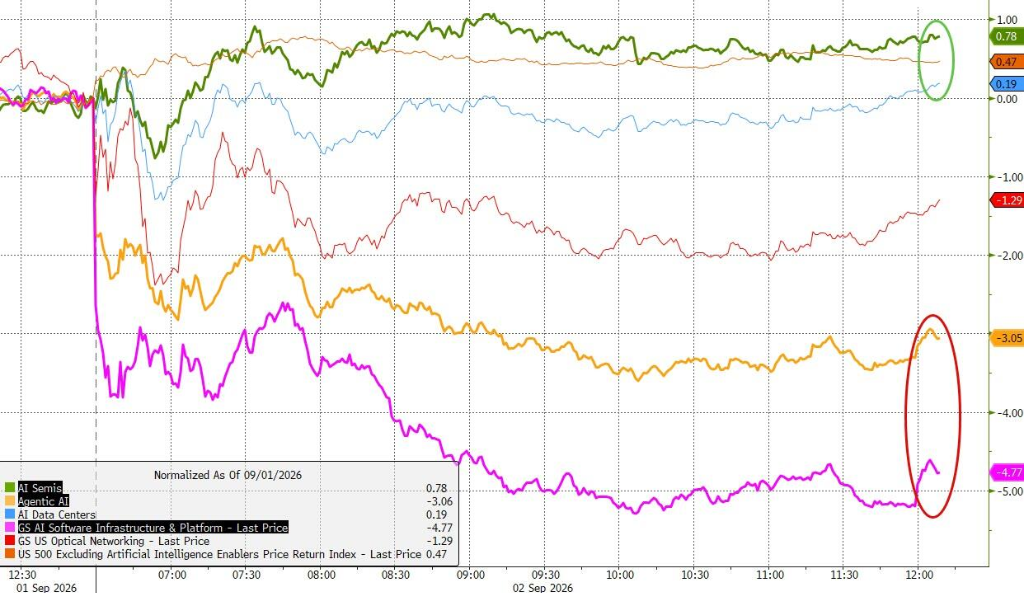
$Credo Technology (CRDO.US)$down 20.04%, marking the largest decline among technology stocks for the day. First-quarter revenue reached $479 million, a year-on-year increase of 114.7%, exceeding market expectations; however, gross margin fell by 3.7 percentage points quarter-on-quarter to 64.5%. Bank of America lowered its target price from $340 to $275.
$MongoDB (MDB.US)$The stock fell 13.54%. Second-quarter revenue reached $771.8 million, a 30.5% year-on-year increase. The company also raised its full-year guidance, but the share price still closed lower. Market concerns focus on earnings quality, as the $153 million in stock-based compensation added back equates to 94% of adjusted net profit.
$Palo Alto Networks(PANW.US)$The stock declined 9.31%. The company's guidance for fiscal year 2027 indicates a slowdown in growth, with revenue growth projected at 23% to 24%, and annualized recurring revenue growth for next-generation security businesses at 22% to 23%.
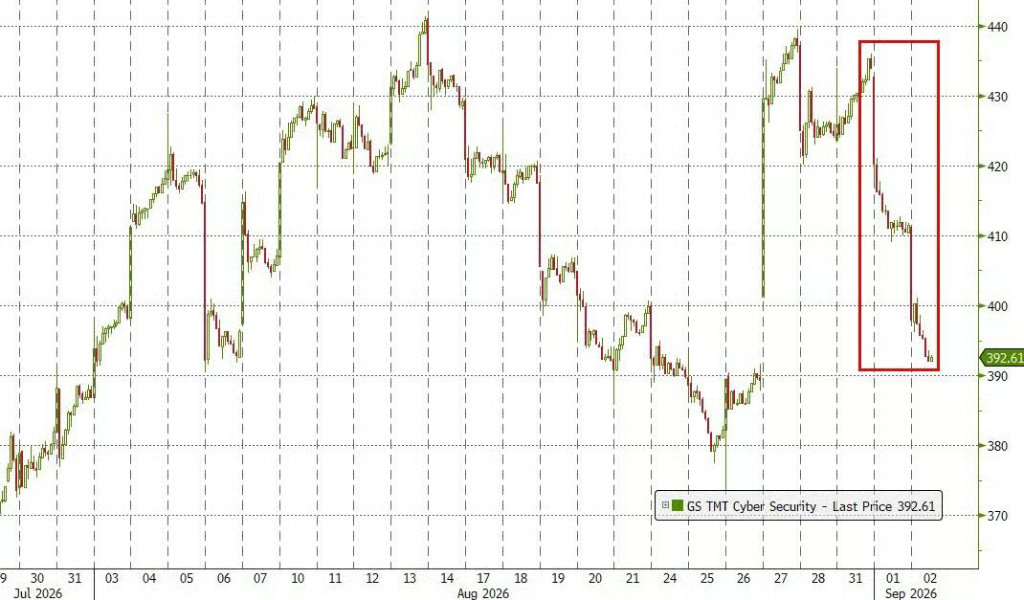
OpenAI released Astra on the same day, featuring advanced cybersecurity capabilities. The market interpreted this as AI companies entering the core business domains of security vendors.$CrowdStrike (CRWD.US)$The Goldman Sachs Cybersecurity Index fell 5.42% to close at 392.61 points.
Global bond markets faced sell-offs, with long-term bond yields in Europe, the UK, and Japan hitting multi-decade highs.
The 'small non-farm' data missed expectations, with US ADP employment increasing by only 38,000 in August, marking the lowest monthly growth since the beginning of the year.
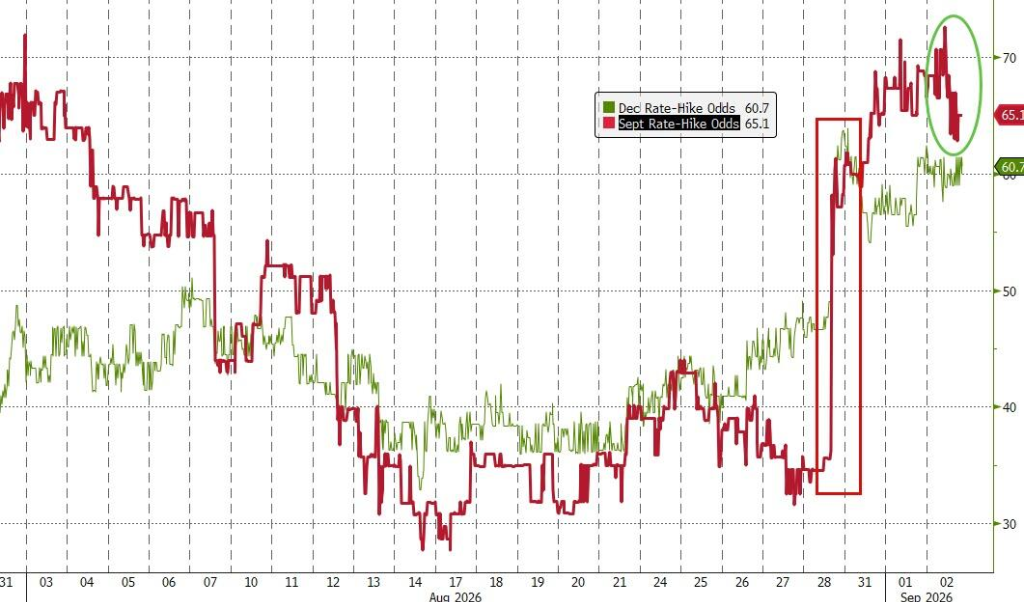
Weak data led the market to lower its expectations for Friday's non-farm payrolls and reignited debate over the Federal Reserve's policy path, shifting focus to the policy trade-off between employment and inflation control. Following the release of macroeconomic data, the probability of a rate hike in September decreased.
The yield on the 10-year US Treasury note rose intraday to 4.816%, touching its highest level since late 2023, before retreating to close at 4.783%, down 1.3 basis points from the previous trading session. The 30-year yield fell 2 basis points to 5.25%.
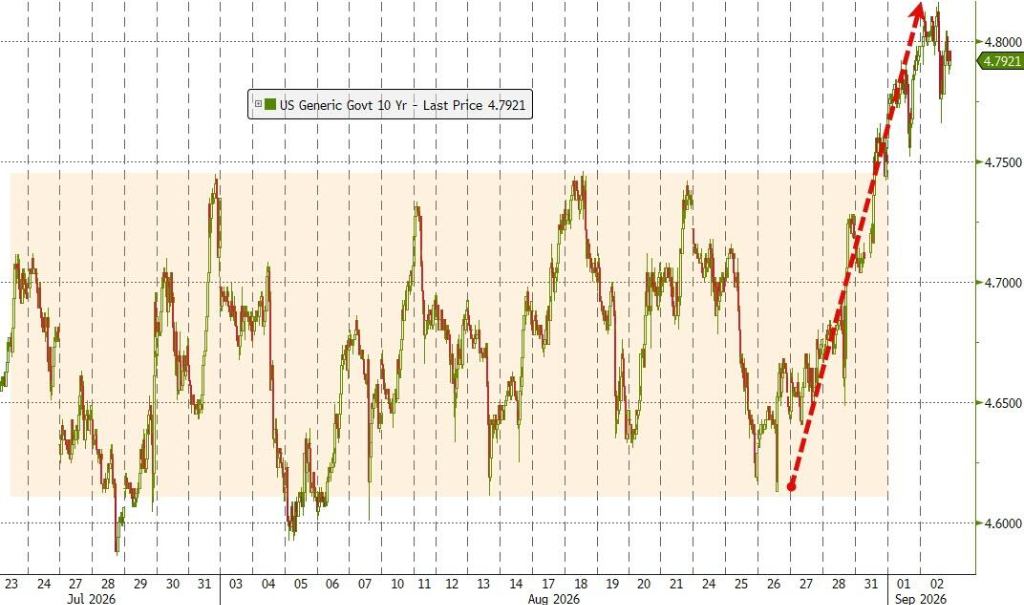
Grace Peters of JPMorgan warned that rising bond yields are the primary risk for global equities in September. With the US 10-year yield approaching 5%, the stock market may experience a 5% to 8% correction before the midterm elections.
Europe presented a different scenario. The Eurozone's Consumer Price Index rose year-on-year from 2.9% to 3.3% in August, the highest since September 2024, driven by the energy component jumping from 10.3% to 14.3%. The market has fully priced in a European Central Bank rate hike in September.
The yield on the UK 10-year gilt rose to 5.294% during trading, returning to levels last seen in August 2007; the 30-year yield climbed to 5.921%, its highest since 1998. Pantheon Macro estimates that the UK Chancellor of the Exchequer has only about £13 billion of fiscal headroom remaining.
$German 10-year government bond yield (DE10Y.BD)$Yields rose 5 basis points to 3.39%, the highest level since 2011. France's 10-year bond yield hit an intraday high not seen since November 2008 before retreating to 4.093% by the close. Italy's 2-year yield climbed to 3.22%, the highest since 2024.
$Japan 10-Year Government Bond Yield (JP10Y.BD)$The yield was quoted at 3.016%, continuing the previous session's trend of breaking above 3% for the first time in thirty years. The 2-year yield rose to 1.86%, the highest in over three decades. The Bloomberg Global Government Bond Index yield stood at 3.72%, returning to 2008 levels.
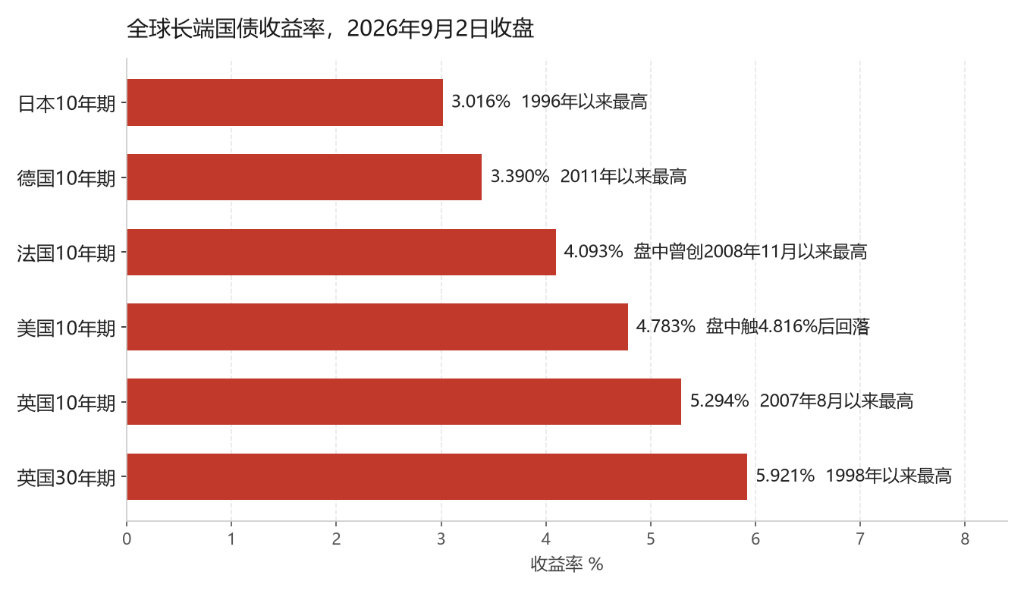
Stephan Kemper of BNP Paribas Wealth Management noted that the current bond market sell-off has been orderly and broad-based, with no signs of credit risk or liquidity crises; the market is merely pricing in persistently higher interest rates. Whether yields will decline depends on inflation expectations.
Gold posts a V-shaped reversal as the yen surges intraday
$U.S. Dollar Index (USDindex.FX)$The index fell 0.11% to 99.51, recording its largest intraday decline since August 21. The USD/JPY pair rose as high as 160.39 during the session, a gain of approximately 1.2%, before plunging from 159.50 to 158.22 within minutes. It closed down 0.89% at 158.71.
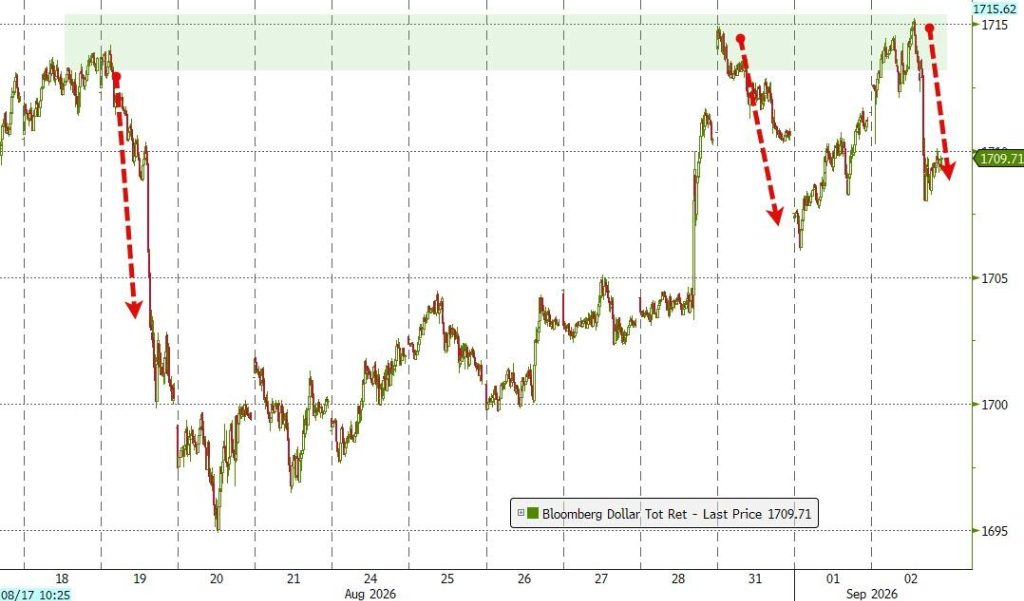
The sharp rise in the yen has sparked speculation of intervention. Japan recently deployed a record $96.4 billion to support its currency last month, keeping markets wary of further entry by the Ministry of Finance. As the dollar weakened, gold strengthened accordingly.
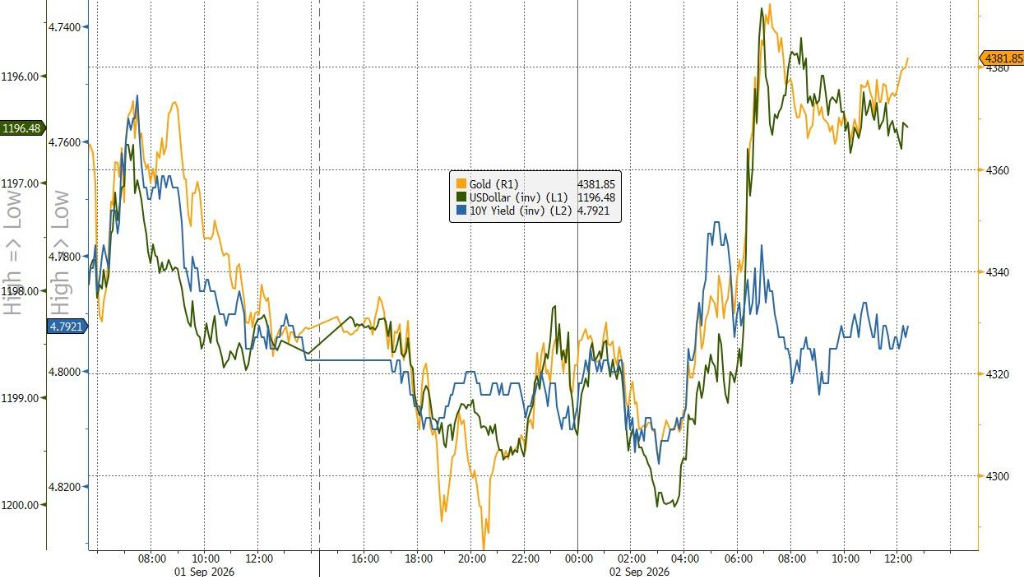
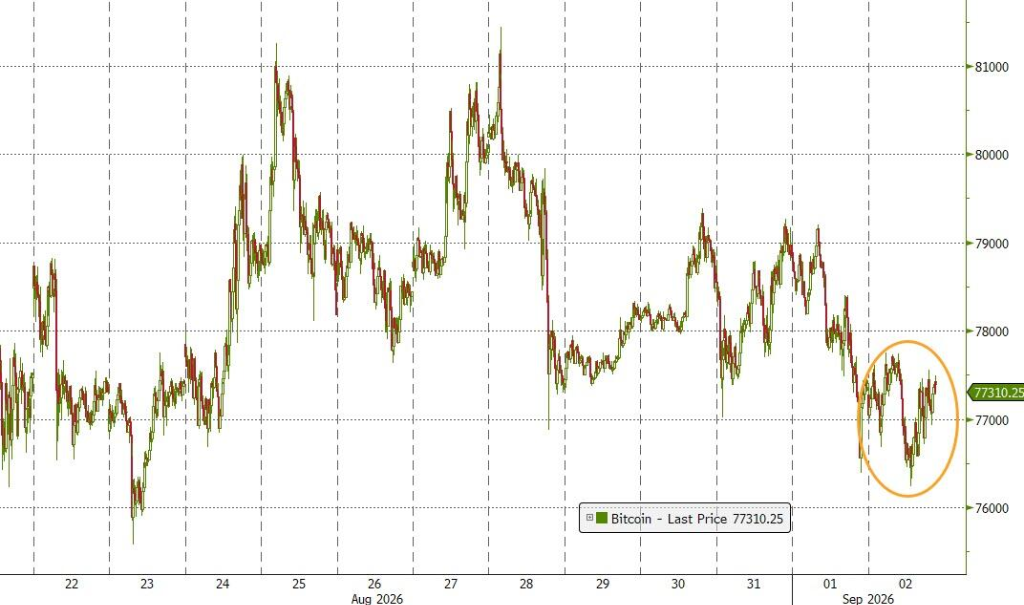
Spot silver rose 1.92% to $65.14. Gold prices followed a V-shaped trajectory, with spot gold hitting an intraday low of $4,282.63, its lowest since August 7, before steadily recovering during the US trading session to rise 1.38%, approaching the $4,400 mark once again.
Company News
[Google Releases Gemini 3.8 Flash and Cybersecurity Model]
On Wednesday, Google released two AI models: Gemini 3.8 Flash and Gemini 3.8 Flash Cyber. Gemini 3.8 Flash primarily enhances capabilities in software engineering, agent tasks, and complex multi-step reasoning, with pricing unchanged from the previous 3.7 Flash version. Gemini 3.8 Flash Cyber is designed for cybersecurity, enabling automated vulnerability discovery and patch generation, and will be prioritized for government agencies, critical infrastructure operators, and software maintenance organizations through the newly launched Fairwind program.
[Australian Rare Earth Giant Lynas Confirms It Engaged in Acquisition Talks This Year]
Australian rare earth producer Lynas Rare Earths stated that the company engaged in acquisition-related negotiations earlier this year, but ultimately did not proceed. Lynas is the largest rare earth producer outside of China. According to insiders, these negotiations prompted Lynas to pause its search for a new CEO to succeed Amanda Lacaze, who retired in June.
【$Uber Technologies (UBER.US)$To cut 10% of staff, focusing on streamlining management layers
Mobility giant Uber Technologies announced on Wednesday that it will cut approximately 10% of its workforce, affecting around 3,300 positions. CEO Dara Khosrowshahi stated that the company will reduce management layers, merge teams, and adjust its global office footprint to concentrate personnel and investment on the most critical growth opportunities. This restructuring is expected to reduce the number of managers at Uber by approximately 20%, while cutting the number of "micro-teams" with only one or two direct reports by nearly half.
Energy storage concept stocks$Eos Energy (EOSE.US)$Surge following partnership agreement with Google
Eos Energy shares closed 18.75% higher on Wednesday. The company announced a partnership with Google and MN8 Energy to develop solar and energy storage projects in West Virginia, USA. The projects include 86 MW of utility-scale solar power, a 10 MW/100 MWh Eos Z3 zinc-based long-duration energy storage system, and a 70 MW/280 MWh lithium-ion energy storage system. This marks Google's first adoption of Eos's aqueous zinc battery energy storage technology.
[Scorpio Gold Soars Over 50% on Positive Gold Mining Drilling Results]
Scorpio Gold, which listed on Nasdaq just last Tuesday, saw its stock price surge 42.32% on Wednesday. The company announced high-grade favorable results from the second phase of drilling at its Manhattan project in Nevada, USA.
[Morgan Stanley:$Nintendo (7974.JP)$Bullish on "The Legend of Zelda" and "Mario" as catalysts for the September Direct presentation]
Morgan Stanley expects that the content of Nintendo's September Nintendo Direct presentation may center around the 40th anniversary of 'The Legend of Zelda' and new games for the Switch 2.
The bank anticipates that the event may unveil a trailer for the live-action "The Legend of Zelda" film, scheduled for release in April 2027, and disclose the launch date and gameplay details for products related to "The Legend of Zelda: Ocarina of Time." Additionally, there is a possibility of an unexpected release of a new 3D "Super Mario" game.
[U.S. Gas Turbine Giant Enters Venezuelan Military Market]
$GE Vernova (GEV.US)$Closed 2.61% higher on Wednesday. The company signed a strategic alliance agreement with Venezuela's state oil company PDVSA and its national electricity corporation Corpoelec to participate in the rehabilitation of Venezuela's severely aging power infrastructure. The agreement involves restoring generation capacity that could reach several gigawatts, with an initial focus on improving the power infrastructure supporting the country's oil industry.
Want to select stocks or get a stock diagnosis? Curious about the opportunities and risks in your portfolio? For all your investment questions,Just ask Futubull AI!
Editor/Liam