
Just six weeks ago, the yen’s exchange rate against the U.S. dollar touched its lowest level in four decades. Today, a confluence of factors is finally shaking the conviction of aggressive short-sellers who have bet on the yen’s depreciation for years, marking a potential turning point for the long-struggling currency.
Zhitong Finance APP reports that just six weeks ago, the yen-to-dollar exchange rate hit its lowest level in four decades. Today, a confluence of factors is finally shaking the confidence of aggressive short-sellers who have bet on yen depreciation for years, marking a potential turning point for the long-struggling currency.
Although the Bank of Japan's interest rate hikes and record-breaking exchange rate interventions previously failed to provide lasting support for the yen, new variables such as capital repatriation, unwinding of carry trades, and political pressure from the United States are forcing speculators shorting the yen to reconsider their long-term strategies.
 "Market sentiment toward the yen appears to be shifting," said Rong Ren Goh, Fixed Income Portfolio Manager at Eastspring Investments. "Investors are increasingly reluctant to aggressively short the yen, especially as the prospect of a Bank of Japan rate hike in September adds new risks to such trades."
The market widely expects the Bank of Japan to raise its benchmark interest rate by 25 basis points this month, but some traders have already begun pricing in expectations of a 50-basis-point hike or a series of rapid consecutive hikes in the coming months. However, under the consistently prudent leadership of Governor Kazuo Ueda, a 50-basis-point hike in September is still considered highly unlikely.
The shift in market sentiment has been corroborated by capital flows. Data from Citigroup shows that yen positions have turned from net short to net long since early August; interbank capital flow data also indicates that leveraged funds, banks, and real-money investors were all net buyers of the yen this week.
The resonance among central bank policies, capital flows, and speculative positions is exacerbating exchange rate volatility. The yen is poised to rise 2.3% against the dollar this week, marking its largest weekly gain since the joint US-Japan intervention in late July. Stephen Jen, CEO and Co-Chief Investment Officer at Eurizon SLJ Asset Management, warned that the risk of a large-scale unwinding of yen carry trades is rising, akin to the forced rapid deleveraging of banks and hedge funds during the collapse of Long-Term Capital Management (LTCM) in 1998.
"When a currency is extremely undervalued and positions are excessively crowded, such volatility tends to occur more frequently before a major market move," Jen said. "It is like an earthquake—tectonic plates are rubbing against each other under immense pressure."
Intervention and the Federal Reserve: Early Signs of Policy Convergence
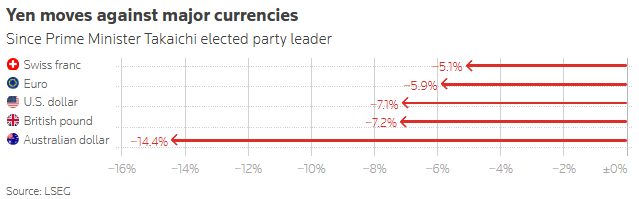
The yen's multi-year depreciation trend accelerated further this year, primarily due to market concerns over the fiscal sustainability of Japanese Prime Minister Sanae Takaichi's stimulus plan, alongside a widespread perception that the Bank of Japan is "behind the curve" in monetary tightening. Between April and May, when the yen fell below the 160 per dollar threshold, the Bank of Japan unilaterally implemented record-scale intervention.
The key turning point for the yen emerged between July and August—after the currency dropped to 163.99 (its lowest level since 1986), the United States rarely joined hands with Japan to implement joint intervention. US Treasury Secretary Scott Bessent, who has long argued that raising interest rates is the correct solution to curb yen weakness, renewed pressure on the Bank of Japan during this week's G20 finance ministers' meeting. Subsequently, Hajime Takata, a member of the Bank of Japan's Policy Board and the sole dissenter against the decision to hold rates steady in July, gave a speech hinting at the possibility of a 50-basis-point rate hike or faster consecutive hikes.
"His remarks regarding consecutive rate hikes and more substantial adjustments were highly impactful," commented Yoshio Iguchi, Chief Strategist at Traders Securities. "If this becomes the consensus, it will be a game-changer for the yen."
According to data from Tokyo Tanshi, the market's probability of the Bank of Japan raising interest rates by 25 basis points to 1.25% in September has risen to 97%, significantly higher than the 52% recorded a month ago. Additionally, the probability of a rate hike in October stands at 27%, while that for December is 56%.
Accelerating Capital Repatriation: Signals of Domestic Institutions' "Homecoming"
Meanwhile, signs indicate that Japanese government bond yields have suddenly surged to historical highs, prompting domestic institutional investors to repatriate funds. In July this year, the Japanese government revealed that its Government Pension Investment Fund (GPIF), with assets under management totaling $1.8 trillion, might shift its asset allocation focus back to the domestic market, a move that triggered volatility in global markets. Official data shows that Japanese investors are reducing their holdings of foreign bonds at the fastest pace in four years.
"The direct driver behind the yen's strength is market speculation that the Bank of Japan may raise rates more than expected, which has clearly captured everyone's attention," stated Bart Wakabayashi, Head of State Street Bank's Tokyo Branch. "However, stepping back, the single largest factor lies in Japanese investors' growing preference for domestic assets, including the liquidation of overseas holdings."
Wakabayashi pointed out that, according to State Street's proprietary data, net short underweight positions in the yen held by real money investors have risen to their highest level in five years, setting the stage for a "reversion" of positions toward neutral or even overweight levels.
The Federal Reserve is also a key variable. Following dovish remarks by Fed Governor Christopher Waller, traders lowered their expectations for a U.S. rate hike this month, creating room for the Bank of Japan to narrow the U.S.-Japan interest rate differential—the primary driver of the yen's weakness. The narrowing of overseas interest rate advantages will also drive the unwinding of carry trades, where investors borrow low-cost yen to invest in higher-yielding overseas assets.
A reversal of short positions could trigger significant market volatility. JPMorgan estimates that since Sanae Takaichi assumed the role of Prime Minister last October, short positions against the yen have accumulated to approximately 17 trillion yen (about $108.74 billion).
"If these positions are fully unwound, the USD/JPY exchange rate could fall to the 142-146 range," wrote JPMorgan analysts Junya Tanase and Ikue Saito in their report.
Edited by Deng