Bessent hopes the U.S. economy will maintain growth of around 3% to ease debt pressures through "growth," but this approach is now being questioned by experts. Economists project that in 2027 and 2028, U.S. GDP growth will barely exceed 2%, net interest payments have already surpassed $1 trillion, and an aging population continues to weigh heavily on public finances. Experts point out that relying solely on growth will not be enough to curb debt expansion; the median forecast for the U.S. deficit-to-GDP ratio in 2028 remains as high as 6.4%.
U.S. Treasury Secretary Bessent has vigorously advocated using economic growth to reduce debt, but this strategy is now facing dual skepticism from budget experts and the market.
Bessent has recently insisted on multiple occasions that, with 3% economic growth and federal spending constraints, the United States could overcome its debt crisis through "growth." However, according to Bloomberg, both the median forecast from economists' surveys and the International Monetary Fund's latest projections indicate that U.S. GDP growth in 2027 and 2028 will be just slightly above 2%, far below the threshold Bessent has set.
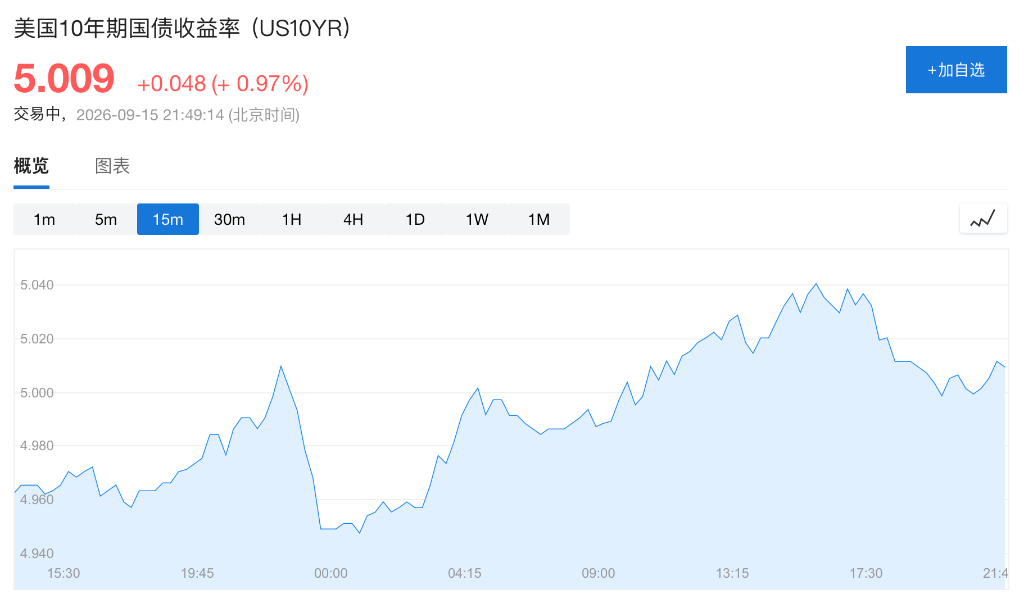
 Greater pressure is already evident in the fiscal interest burden. This fiscal year, U.S. net interest expenditures have reached $1.02 trillion, up 8.9% year over year, surpassing $1 trillion for the first time. Meanwhile, the yield on the 10-year U.S. Treasury bond—previously regarded by Bessent as a key indicator—has broken through 5%, hitting levels not seen since the early 2000s.
Historical data does not support the "growth‑to‑debt‑reduction" logic.
The analysis indicates that even during periods of relatively strong economic performance in recent years, economic growth has failed to curb the expansion of debt. In 2023 and 2024, the U.S. economy posted real growth rates close to 3%, yet federal debt held by the public increased by approximately 10% and 7%, respectively, with annual budget deficits exceeding $1.6 trillion each year, and the debt-to-GDP ratio continuing to rise.
In the late 1990s, U.S. GDP growth once exceeded 4%, but the fiscal surplus at that time was achieved through a combination of tax hikes and reduced defense spending following the end of the Cold War. Today, both of these conditions no longer exist—multiple rounds of tax cuts have sharply lowered tax rates, and in recent years, both parties have generally favored increasing rather than cutting federal spending. Meanwhile, amid heightened geopolitical tensions, Trump has also sought congressional approval for a $1.5 trillion defense budget, a 44% increase over the previous level.
Douglas Holtz-Eakin, chairman of the American Action Forum and former director of the Congressional Budget Office, stated bluntly: "You cannot solve this problem through growth alone; it simply doesn't add up numerically." He calculated that, if relying solely on growth to bring the deficit down to the target level set by Bessent, the U.S. economy would need to grow at a rate of 6%. Moreover, given population aging and immigration restrictions, even achieving 3% growth would be nothing short of a "miracle."
Population aging and interest expenditures constitute structural pressures.
One of the core contradictions in the debt issue lies in demographic trends. From the start of Trump's current term through May this year, the number of Social Security retirees increased by 2.8 million, while the number of working taxpayers rose by only 593,000. Social Security and healthcare are the two largest expenditures in the federal budget, and Trump has made it clear that he will not cut benefits, nor is there any sign that Congress is pushing for major reforms.
Holtz-Eakin points out that even if the economy grows at a real rate of 3% and inflation runs at 2%, yielding 5% nominal growth, tax revenues would only keep roughly pace with nominal GDP, while Social Security spending would rise at an average of 5.5%, and Medicare spending would climb even faster, at 7.5%. "Thus, the problem simply cannot be resolved."
Interest expenses also represent a substantial burden. With one month remaining in the current fiscal year, net interest outlays have already reached $1.02 trillion, up 8.9% year over year. As of the end of August, the average yield on outstanding U.S. Treasury debt stood at 3.48%, while the benchmark 5-year Treasury yield currently hovers around 4.77%. This yield spread suggests that, as maturing bonds are refinanced, the government's future interest burden could continue to rise.
Expert: Relying solely on growth is not enough to solve the problem.
Bessent's former advisor, Joe Lavorgna, acknowledged that growth is an important component of reducing the deficit, but admitted, "growth alone may not be enough," and "you may need more than just growth."
Maya MacGuineas, president of the Committee for a Responsible Federal Budget, stated: "There is no credible estimate suggesting that growth can magically erase fiscal problems." The organization also warned against Trump's proposal to issue $5,000 checks to every adult citizen, estimating that the plan would cost as much as $1.2 trillion in a single year and push the deficit-to-GDP ratio up to 9% to 10%.
Seth Carpenter, Morgan Stanley's chief global economist and a former Treasury official in the Obama administration, pointed out that growth-based fiscal consolidation is "very likely," but this hinges on fiscal policy no longer shifting toward expansion—"and that, to me, is the real sticking point."
When Bessent took office, she set a goal of reducing the deficit-to-GDP ratio to around 3% before the end of Trump's term. However, according to a Bloomberg survey, economists' median forecast for the deficit ratio in 2028 is 6.4%, with the lowest estimate at 4.5% and the highest at 8%—all significantly above Bessent's target.
Editor/Deng