U.S. stocks staged a rather robust rally on Thursday—despite the Federal Reserve having just delivered its first rate hike since July 2023 just one day earlier.
All three major stock indexes closed higher. The S&P 500 gained 1.1%, with the Nasdaq Composite leading the way up 1.7%, while the Dow Jones Industrial Average rose 316 points, a gain of 0.6%. The Russell 2000 index, which tracks small- and mid-cap stocks, ended the day up 0.5%. Of the S&P 500's 11 sectors, nine closed in positive territory, but the bulk of the momentum was concentrated in technology stocks—$NVIDIA (NVDA.US)$ 、 $Amazon (AMZN.US)$ 、 $Microsoft (MSFT.US)$ 、 $Intel (INTC.US)$and$Advanced Micro Devices (AMD.US)$All recorded significant increases.
"Earlier, the market had anticipated a Fed rate hike, sending many sectors sharply lower; now, capital is starting to flow back in," said Robert Pavlik, senior portfolio manager at Dakota Wealth in Fairfield, Connecticut. "And today, many investors are taking advantage of the pullback to buy on dips."
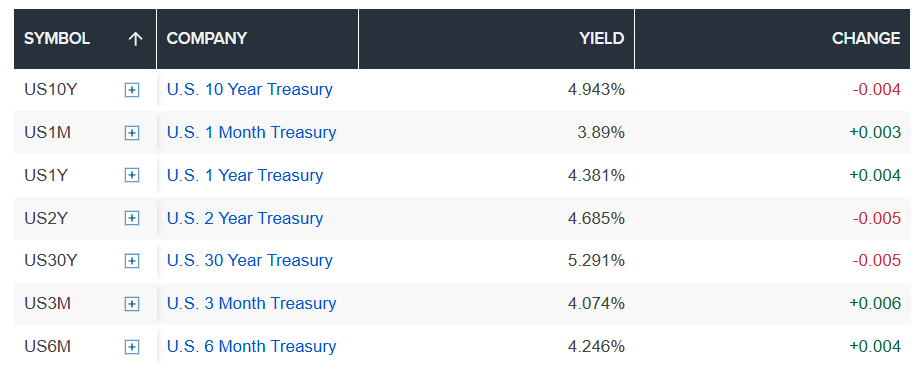
 As stocks rally, bonds are also climbing—a rare occurrence following a "hawkish" rate hike by the Federal Reserve. The yield on the 10-year U.S. Treasury fell from Wednesday's peak of 5.02% to a low of 4.93%, while the 30-year yield dropped from 5.36% to 5.27%. Meanwhile, U.S. crude oil briefly dipped below $100 per barrel for the first time since last Friday. These seemingly contradictory positive developments unfolding in tandem have given rise to a multi‑layered narrative about what markets are pricing in the wake of the rate hike.
Oil Prices Are Retreating: Geopolitical Pricing Is Easing
The most immediate external driver of this round of rebound stems from the cooling in the crude oil market.
During Thursday's trading session, U.S. WTI crude oil briefly fell below the $100 mark, while Brent crude dipped as low as $101—just two days earlier, Brent had been trading above $109. By the close, WTI's losses had narrowed, down 0.5% to $101.91, and Brent was off 0.9% at $104.82.
Two downward trends in oil prices resonated on the day. First, reports indicated that President Trump is expected to meet with the leaders of the six Gulf Cooperation Council countries during the United Nations General Assembly in New York next week to discuss the next steps in the Iran conflict. Trump himself told reporters, "I hope we are nearing the end of the war."
Second, Saudi Aramco is working to bypass the east–west pipeline section that was damaged in the attack and plans to restore roughly half of its capacity within a few days—equivalent to 2 to 2.5 million barrels per day. While full repairs are expected to take about six weeks, news of a "partial resumption of production" has been enough to ease the market's most pressing concerns over a short-term supply disruption.
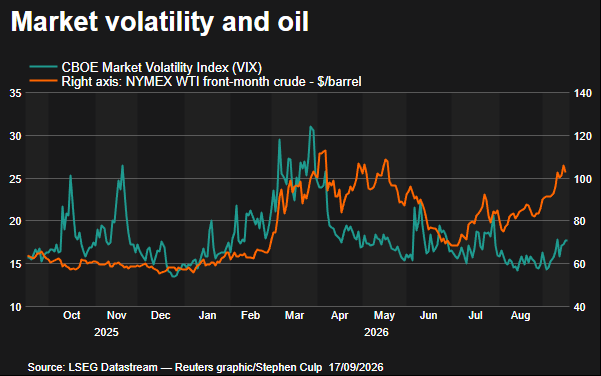
However, the absolute level of oil prices remains unsettling. So far this year, both WTI and Brent have risen by more than 70% cumulatively. On Thursday, the average U.S. retail gasoline price increased by another 7 cents to $4.43 per gallon, while the average diesel price jumped by 8 cents to $6.39, up 93 cents from a month earlier.
Baird investment strategy analyst Ross Mayfield described the oil price shock as "the single most significant headwind currently facing the global economy." He added, "When an oil price shock persists for so long, it inevitably permeates the entire economy's pricing system. However, any easing—whether beneficial to consumers or to businesses—could also prompt the Federal Reserve to adopt a less hawkish stance."
A "Respite" in U.S. Treasury Yields
The bond market's reaction is equally crucial. Against the backdrop of the Fed's rate hike and the dot plot signaling another increase within the year, U.S. Treasury yields have declined, seemingly sending a nuanced signal: easing macroeconomic uncertainty has reassured investors, while the hawkish tone of Chairman Powell's Wednesday press conference has been gradually priced in by the market.
The newly appointed Federal Reserve Director Kevin Warsh adopted a "restrained hawkish" stance at his first press conference, which was well-received by the market. Krishna Guha, Vice Chairman of Evercore ISI, commented: "Warsh's press conference was clear and confident, maintaining a consistent hawkish position without coming across as overly aggressive."
ABN-AMRO economist Rogier Quaedvlieg offered a different perspective: "Walsh withstood pressure from the Trump administration and upheld the Fed's credibility by delivering on its earlier signals of rate hikes." Chris Zaccarelli, chief investment officer at Northlight Asset Management, put it more vividly: "Walsh walked a tightrope and handled it impeccably."
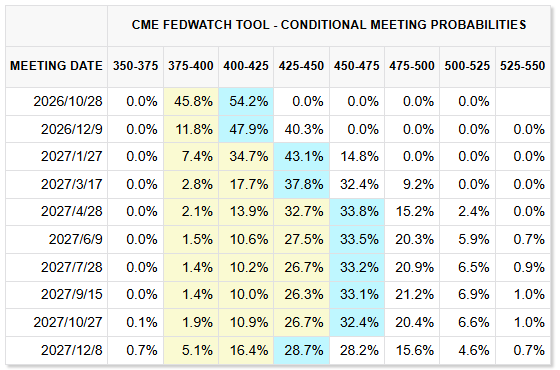
Market pricing is also adjusting rapidly. According to the CME FedWatch tool, traders now price in roughly a 54% probability of another 25-basis-point rate hike at the October meeting, up from just 27% a week ago. In other words, the market is indeed gradually coming to terms with the reality that the hiking cycle is not yet over—but it is doing so in a measured, orderly manner, rather than in a panic.
Overseas bond markets are also responding to this easing of sentiment. On Thursday, the Bank of England voted 6–3 to keep its key interest rate unchanged at 3.75%, while unexpectedly abandoning plans to sell long-term UK government bonds and instead announcing that it will hold roughly £222 billion of bonds maturing between 2026 and 2034 until their maturities. This shift pushed the yield on UK 30-year gilts down by 4 basis points to 5.82%, and the 10-year yield fell to 5.262%.
Jensen Huang's "doubling" expectation: emotional repair in the AI narrative
Beyond the macro-level tailwinds, there's a more specific catalyst driving the tech sector's rally: NVIDIA CEO Jensen Huang stated at an event in Scotland convened by King Charles III that he expects the company's chip sales next year to be double this year's.
"AI is delivering tremendous value across diverse industries and economies. You can see it in nearly every country where we operate—people are eager to invest in AI," said Jensen Huang. He also noted that the current bottleneck is not demand, but NVIDIA's capacity to manufacture chips.
This statement is far from unfounded. NVIDIA had previously projected that, for the fiscal year ending January 2028, revenue growth would reach approximately 70%, with revenues totaling about $673 billion. Meanwhile, Jensen Huang revealed last autumn that the company had delivered 6 million Blackwell GPUs over four quarters. This latest claim of "doubling sales" further bolsters market confidence in the sustainability of the AI infrastructure investment cycle.
Bounce or reversal?
Thursday's market action can easily give the impression that the alarm has been lifted. However, several factors warrant caution.
Jefferies' strategy research offers a less reassuring historical benchmark: in the month following the first rate hike, the S&P 500 posted an average return of –1.6%; three months later, the average return was –4.2%, marking the weakest performance across all periods.
Jane Gibbons, a stock strategist at the firm, stated: "Looking back at the historical returns of the S&P 500 during interest-rate hike cycles since 1983, rate hikes have not been favorable for equity market performance."
Analysts note that following the September rate hike, the market may exhibit a short‑term rebound; however, both the durability and resilience of such a rally are likely to be limited. The rationale is that the nature of this tightening cycle has shifted: with employment data exceeding expectations and Middle East tensions driving up energy prices, the rate hikes can no longer be characterized as purely "preemptive." Instead, they reflect a more reactive response to recent economic data, and the risk of policy lags—where the pace of tightening trails the underlying economic trajectory—is increasing.
Morgan Stanley, JPMorgan, and Goldman Sachs, on the other hand, adopt a relatively optimistic stance, believing that the market has already priced in the policy shift, and that corporate earnings and economic growth remain the primary drivers supporting the stock market; a single rate hike is unlikely to alter the medium-term trajectory of this rally.
Goldman Sachs noted in a research report that high interest rates are a headwind for the stock market, but they are not enough to bring the bull market to an end. As long as earnings growth remains robust and corporate balance sheets stay healthy, the U.S. stock market's bull run has a solid foundation to continue.
The tension between the two scenarios hinges essentially on one key variable: how long oil prices remain at elevated levels. If the U.S.-Iran conflict makes substantial progress on the diplomatic front—Trump's meeting with Gulf-state leaders next week will serve as a useful gauge—then inflation expectations could ease, and the Fed's rate-hike path would likely become more moderate. Conversely, if oil prices continue to hover above $100 per barrel, the shift of high interest rates from a "risk scenario" to a "baseline scenario" would exert sustained downward pressure on valuations.
Triple Witching Day叠加:Friday's market faces a liquidity test
But for tonight, Wall Street is bracing for potential volatility. On Friday, U.S. stocks will mark the quarterly "Triple Witching Day," when index futures, index options, and individual stock options all expire simultaneously.
According to Bluekurtic Market Insights, its historical performance has been notoriously poor. Data tracking performance since 2000 reveal a remarkably consistent trend: since 2012, the S&P 500 has closed lower on 12 out of 14 "Triple Witching" days.
During this period, the only two exceptions occurred in 2017 and 2025, when the index posted modest gains of 0.2% and 0.5%, respectively.
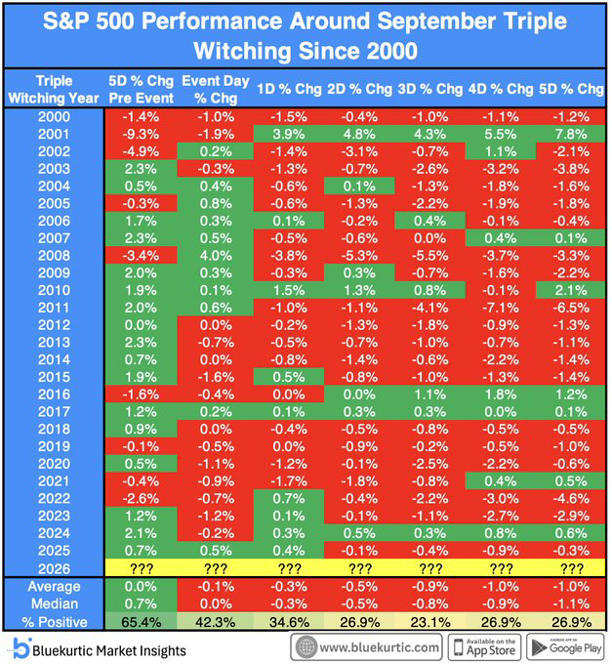
As options with a notional delta exceeding $2 trillion approach expiration, market observers warn that this quarterly liquidity event could trigger downside volatility.
This upcoming expiration event comes at a time when the stock market is facing its most challenging month on record. Although the S&P 500 has so far weathered these seasonal headwinds with an unusually subdued gain of just 0.3%, Friday's massive expiration could prove to be the ultimate test of the month's performance to date.
Want to pick stocks or analyze them? Looking to understand your portfolio's opportunities and risks? For all your investment questions,Just ask Futubull AI!
Editor/joryn